Oil Near $100 — Five Bills Coming Due for South Korea
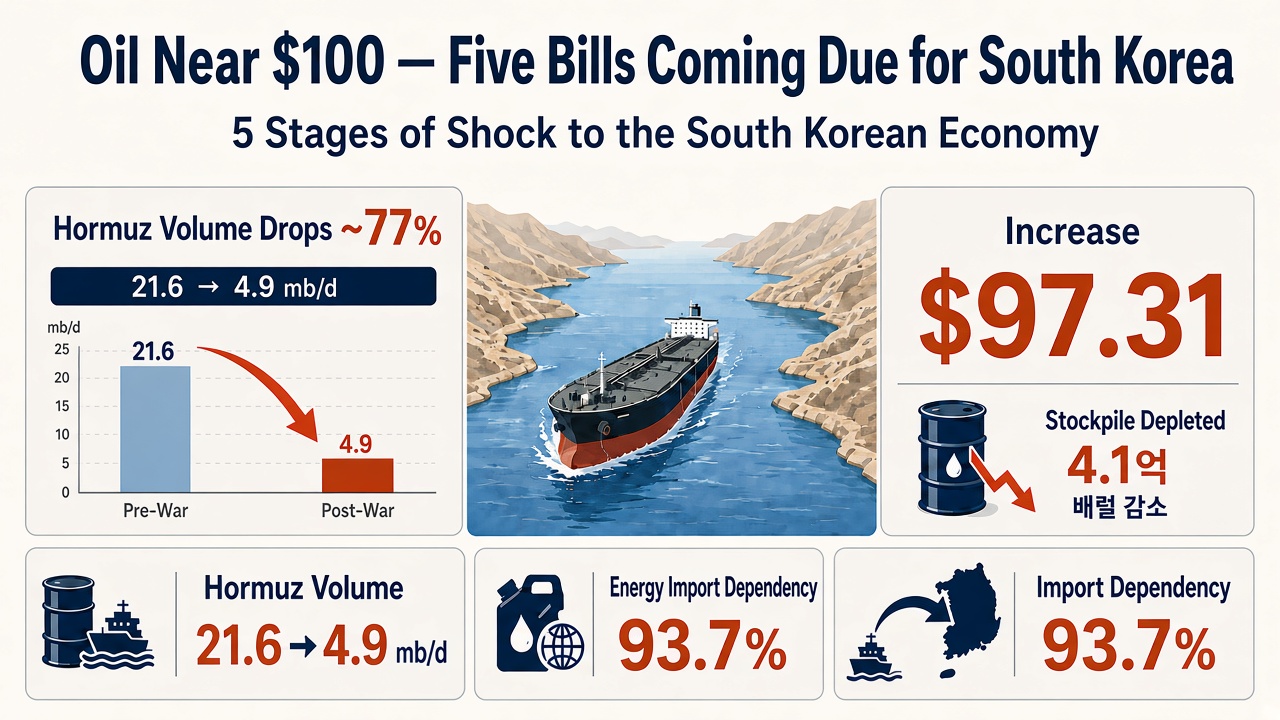
Oil at $100 is back within sight. Brent settled at $97.31 a barrel on September 7, 2026, after touching $98.06 intraday. For South Korea, this is not merely a gasoline story. The shock can travel through the import bill, the won, company margins, household spending, interest rates, and equities.
This move is more than a fear premium. Physical oil flows have fallen, production has been shut in, and inventories are being depleted. This article separates what is known from what remains a forecast.
Why oil near $100 carries more weight this time
Oil prices respond to the gap between barrels needed today and barrels available today. A tanker attack matters mainly when it stops shipping, deprives producers of storage, and forces wells to shut.
The U.S. Energy Information Administration estimates that crude oil and petroleum-liquid flows through the Strait of Hormuz fell from 21.6 million barrels per day in the fourth quarter of 2025 to 4.9 million in the second quarter of 2026. That is a drop of roughly 77%.
Inventories are also thinner. The International Energy Agency says observed global oil stocks fell by 69 million barrels in July and by 410 million barrels since the war began. A full warehouse absorbs disruption. An emptying one makes prices react sharply to the next incident.
-
1
Shipping disruption
Hormuz flows plunge
-
2
Production shut-ins
No outlet for barrels
-
3
Inventory draw
410m barrels since war
-
4
Prices and margins
Crude and fuels tighten
Crude scarcity is only half the story
Crude cannot be poured directly into a car or aircraft. Refineries turn it into gasoline, diesel, and jet fuel. The gap between crude costs and product prices is the refining margin. When refineries or product shipping are constrained, fuel can remain expensive even if crude eases.
The IEA says July refinery throughput was almost 5 million barrels per day below a year earlier. Diesel exports from Russia, the Middle East, and Asia were down 1.3 million barrels per day, about 20% of global seaborne diesel trade.
The World Bank’s September update points in the same direction: crude rose 5.7% in August, while its energy index climbed 8.8% and natural gas rose 10.1%. One bottleneck is spreading into transport, power, and fertilizer costs.
How the shock reaches South Korea
South Korea imports 93.7% of its energy, and oil supplies 37.6% of primary energy. Diversification toward the Americas and Asia helps, but the Middle East still supplied 71.9% of crude imports in 2023.
The transmission chain is straightforward. Refiners buy crude in dollars. A larger import bill can narrow the trade surplus and add pressure on the won. A weaker won then makes the same $97 barrel more expensive in local currency. Oil and the exchange rate can reinforce each other.
-
1
Import bill
More dollar spending
-
2
Trade and won
Depreciation pressure
-
3
Business costs
Fuel, freight, inputs
-
4
Consumer prices
Pass-through with lag
-
5
Spending, rates, stocks
Weaker demand, higher rates
Companies initially absorb higher freight, packaging, feedstock, power, and gas costs through lower margins. If the shock persists, they raise prices. Households then spend more on fuel and essentials and less elsewhere.
Our earlier explainers on the won-dollar exchange rate and KOSPI volatility provide more detail on those two channels.
Winners, losers, and important exceptions
Refiners are not automatic winners. A rapid oil rise may generate inventory gains, and scarce diesel or jet fuel can widen refining margins. Yet interrupted crude supply or stronger price controls can shorten that favorable window.
Petrochemicals face a different equation. If naphtha feedstock costs rise while oversupply and weak demand prevent product-price increases, margins shrink. Refining and chemicals can therefore move in opposite directions even inside the same company.
Airlines, shipping, trucking, packaging, and food producers are exposed through fuel or logistics. Firms with fuel surcharges and pricing power can pass on part of the increase. Those locked into fixed-price contracts absorb it first.
Potential buffers
Inventory gains, wider cracks
Refining
Efficiency · Demand for savings
Cost pressure first
Higher naphtha cost
Petrochemicals
Airlines and transport · Higher fuel expense
Domestic demand · Less discretionary income
Investment responds more slowly. A brief spike rarely cancels a factory. If oil and the exchange rate stay high for two quarters, cash-constrained companies may postpone expansion and cut inventories. Spending on energy efficiency, grid equipment, storage, and fuel-saving ships may accelerate instead.
Consumption, inflation, and rates move with a lag
The Bank of Korea forecasts 2026 headline inflation at 2.7% and says the oil shock can spread into non-petroleum goods and services. Its prolonged-conflict scenario adds 0.3 percentage point to 2026 inflation and 0.5 point in 2027 versus the baseline.
The key word is lag. Retail inventories, supply contracts, taxes, and regulated tariffs prevent an instant pass-through. The reverse is also true: restaurant prices and freight charges may not fall promptly after crude does.
For households, expensive energy behaves like an invisible tax. Money spent commuting or heating cannot be spent on restaurants, clothes, or leisure. Growth weakens while inflation stays firm, making rate cuts harder.
Equities price both earnings and discount rates
Higher oil lowers expected earnings for cost-sensitive firms. It can also push bond yields higher through inflation fears, raising the discount rate used to value future profits. That second channel explains why long-duration growth stocks can react to oil headlines.
A weaker won may lift exporters’ translated revenue, but it raises costs for companies buying inputs and equipment in dollars. Investors need to examine revenue currency, input currency, pricing power, and hedges rather than assuming every exporter benefits.
The verified facts are that Brent is in the high $90s and inventories have fallen. A rally in refiners or a decline in airlines is a market inference, not a fact. Prices may already reflect it, and diplomacy can reverse the trade quickly. This is not investment advice.
Four signals that would confirm a real turn
The EIA forecasts Brent at an average $78 in the fourth quarter of 2026 and $69 in 2027, conditional on Hormuz traffic recovering gradually from September. The condition matters more than the target.
- Actual tanker traffic through Hormuz and Bab el-Mandeb
- Restart of shut-in Gulf production
- A turn from global inventory draws to builds
- Normalization in diesel and jet-fuel margins and shipping rates
A ceasefire headline is not enough. Ships must move, wells must restart, and storage tanks must refill before a price decline can be called supply normalization.
The number that matters more than $100
The $100 line is memorable, but duration matters more. A few days above $100 may hurt less than two quarters in the $90s. For Korea, the important dashboard is tanker traffic, inventories, refining margins, and the won—not one round number.
Sources and further reading
- Reuters, September 7, 2026 oil-market report
- IEA Oil Market Report and maritime chokepoint monitor
- EIA Short-Term Energy Outlook, August 2026
- World Bank Commodity Markets, September 2026
- Bank of Korea Economic Outlook, May 2026
- Korea Energy Agency and KEEI statistics
Duration matters more than the round $100 line.
Sources
- Reuters — Oil prices rise to six-week highs, September 7, 2026
- IEA — Middle East Maritime Chokepoints Shipping Monitor
- IEA — Oil Market Report, August 2026
- EIA — Short-Term Energy Outlook: Global oil markets
- EIA — Short-Term Energy Outlook, August 2026
- World Bank — Commodity Markets, September 2026
- Bank of Korea — Korea Economic Outlook, May 2026
- Korea Energy Agency — National energy statistics
- Korea Energy Agency and KEEI — Crude sourcing and refining statistics
- KEEI — Energy Supply and Demand Trends, August 2026
- IMF — Managing Director statement after the G20 meeting
For information only — this is not a recommendation to buy or sell any asset.
Comments 0