KOSDAQ’s 8% Surge — PER, PBR & Whether the Rally Has Room
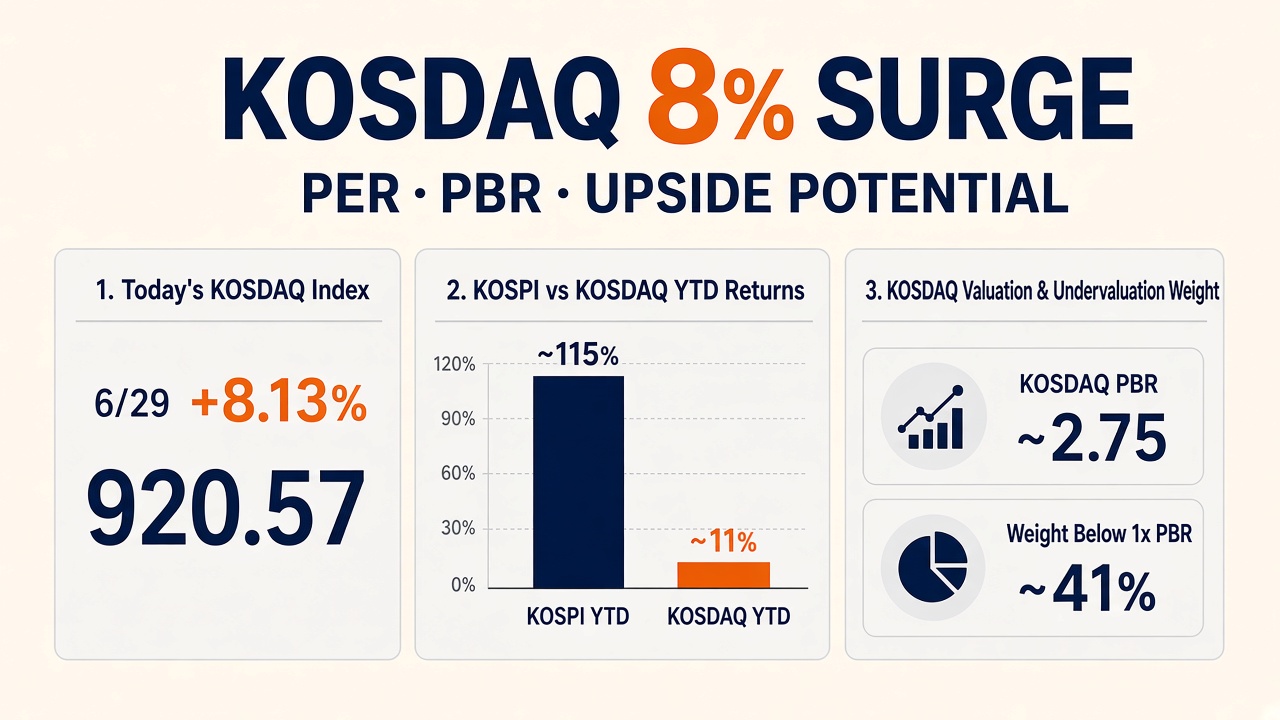
On 29 June 2026, the KOSDAQ closed +8.13% at 920.57. Korea Exchange triggered a buy-side sidecar — the 16th of the year (Newsworks).
The same day KOSPI slipped -0.20%. Brokers described rotation from semiconductors into batteries and bio — not a broad fundamental upgrade. +8% was real that day; it is not every day — on 17 June KOSDAQ rose only +1.30%; on 22 June it fell -7.94% below 900 (MoneyToday).
The question: after a day like this, is KOSDAQ cheap enough to keep rising, or cheap-looking with weak earnings? You need PER, PBR, profits, and flows — not the headline % alone.
Not investment advice. Commentary from public data and press reports.
What the 8% day was
In short: short-term rotation from KOSPI to KOSDAQ. Foreigners bought KOSDAQ while trimming large-cap KOSPI; batteries and bio led. The move looks more like theme chase + bounce from fear than a market-wide earnings surprise.
KOSPI vs KOSDAQ — YTD gap
Mid-June press bundles put KOSPI YTD near +115% vs KOSDAQ near +11% — a 100+ percentage-point gap (Maeil Business). 2026 net-income consensus: ~727T KRW KOSPI vs ~10T KOSDAQ (~73×). Q1 operating profit: 156T vs 4T (MoneyToday). An 8% index day does not mean profits rose 8%.
YTD return gap — chart
2026 KOSPI vs KOSDAQ year-to-date return gap. YTD index returns (%) cited in Korean press mid-June 2026. Figures move with dates. Not advice.
Index PER & PBR — cheap KOSDAQ, with traps
KOSDAQ index PBR hovered around ~2.3–2.8× in H1 2026, yet ~41% of listings trade below 1.0× PBR (Herald). The index looks “expensive”; most stocks look below book — classic concentration + loss-making tail.
In May 2026 KOSPI index PBR overtook KOSDAQ for the first time in ~15 years (etoday). “KOSDAQ is cheaper” is now a stock-picking claim, not an index call. KOSDAQ index PER is distorted when earnings are tiny or negative; diluted PCR is proposed as a cleaner screen (MK/KIS).
Sector PER — what KOSDAQ prices in
QuantNova (29 Jun 2026, 5Y-normalized): pharma ~26× PER, -4.5% ROE; semi equipment ~42×; 2nd battery ~32×, -1.6% ROE; AI/robot ~38–42×, negative ROE. The sectors that led +8% already carry growth multiples without average profitability. Further upside needs earnings upgrades; KOSDAQ revisions are still skewed down vs KOSPI (MK).
Sector PER — chart
KOSDAQ sector average PER pharma semi equipment battery. 5Y-normalized avg PER by sector/theme (QuantNova 2026-06-29). Loss-making sectors distort PER.
Flows, margin debt & policy
Margin debt has left KOSDAQ while piling into KOSPI (MT). Foreigners often lead one-day spikes. Segment reform / Select league (~70 names) may re-rate leaders, not the whole 1,800+ pool (Sedaily, ETNews). Low-PBR tagging starts July (Herald).
Upside — three scenarios
Scenario probability — chart
KOSDAQ upside scenario probability author judgment. Relative probability (%, sum 100) for H2 KOSDAQ paths. Author judgment. Not advice.
Checklist after +8%
Stock-level PER+ROE+cash flow; earnings revision direction; rotation vs trend; foreign/margin flows for two weeks; reform tier impact; is +8% a new leg or an escape from 900?
Wrap-up
+8% KOSDAQ is mostly flow speed — KOSPI fatigue, theme rotation, bounce from fear — not an 8% one-day macro improvement. Upside is possible via gap, foreigners, and Select-league narrative; sustained upside needs KOSDAQ earnings upgrades and returning retail leverage.
One line. +8% is a flow speedometer, not a financial statement. Use PER/PBR to guess who sells tomorrow.
+8% on KOSDAQ is a flow speedometer — PER and PBR tell you who might sell next.
Sources
- Newsworks — KOSDAQ +8.13% Jun 29
- MK — KOSPI vs KOSDAQ YTD gap
- MoneyToday — KOSDAQ below 900
- QuantNova — sector PER/PBR
- Herald — PBR below 1 breadth
- etoday — KOSPI PBR overtook KOSDAQ
- MoneyToday — KOSDAQ segment reform
- Internal: 2026-06-29-kosdaq-surge-per-valuation-session-01.md
For information only — this is not a recommendation to buy or sell any asset.
Comments 0