KRW Breaks 1,500 — Corporate FX Policy & H2 Rate Odds
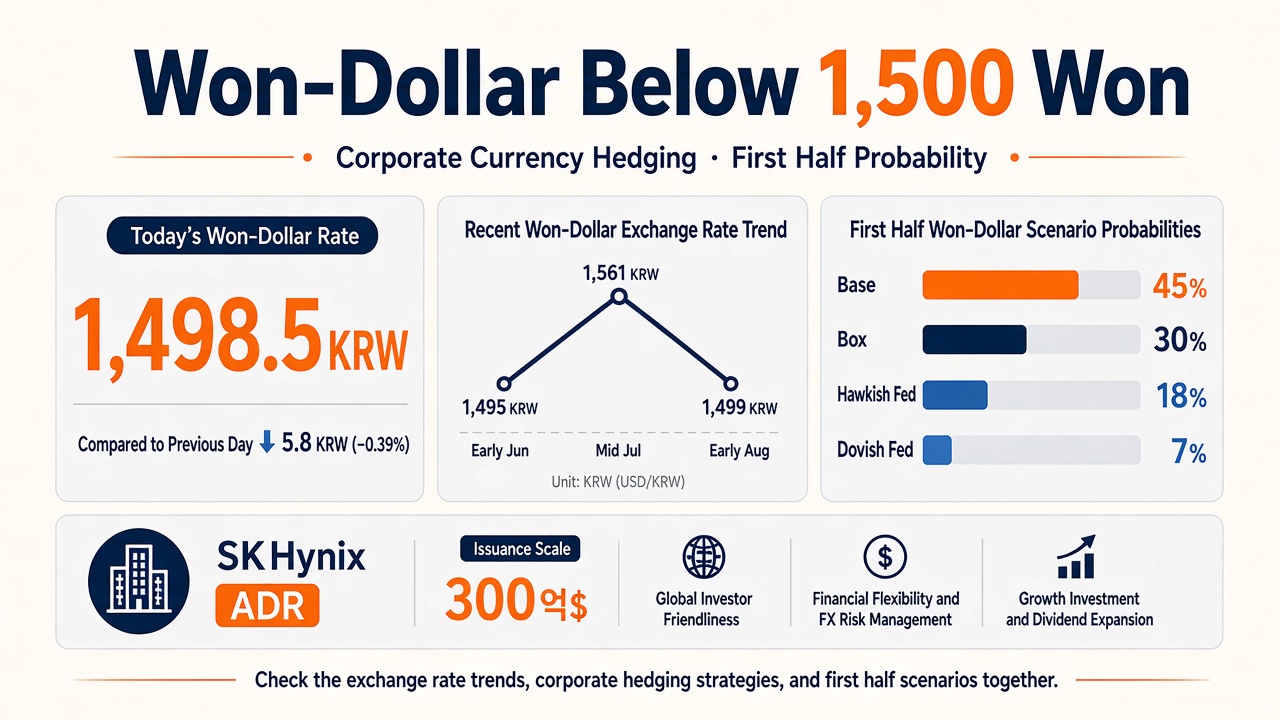
On July 8, 2026, USD/KRW closed at 1,498.5 — the first finish below 1,500 in about 40 sessions. After printing 1,559 earlier in July, the break came as markets priced SK hynix’s up-to-$30B ADR, foreign net buying, and months of government nudges for exporters to sell dollars.
A lower USD/KRW means a stronger won. This piece maps the H1 supply paradox, corporate FX policy, stakeholder wins/losses, broker H2 views, and four scenario probabilities.
Not investment or FX advice. Odds are author weights and can change quickly.
Why 1,500 stuck — supply paradox
Record exports met a 17-year weak won because dollars stalled in corporate accounts ($54.4B at major banks, Jun 11) while foreigners sold equities and retail bought abroad. Export booms do not automatically strengthen the won.
-
1
① Exports
Semis·ships boom
-
2
② Corp FX acct
USD deposits abroad
-
3
③ Conversion
Delay·split·hedge
-
4
④ FX market
USD sell → KRW bid
What changed Jul 8
Foreign ₩331.1B net buy on KOSPI · ADR front-running (listing Jul 10, FX from ~Jul 15) · follow-on exporter USD sales · yen/USD moves helping KRW.
Korea FX path — at a glance
May ~1,495 → Jun peak 1,561 → Jul 1 1,559 → Jul 8 ~1,499. V-shaped, but not yet a confirmed trend reversal.
2026 H1 USD/KRW path. Key 2026 USD/KRW levels (KRW). Lower = stronger won. Mixed close/intraday sources. · Axis starts at 1,400, not zero
Govt push for corporate FX conversion
Jun 11 meeting with Samsung, SK hynix, Hyundai·Kia, top shippers — early conversion of export proceeds and repatriation of offshore cash. Daily FX/hedge monitoring since late June. No legal mandate since 2017 FX law change. Critics call it asking firms to be the govt’s ATM.
What govt wants
Exit 1,500 band, less vol
Goal
Tools · Meetings·daily checks·split FX
Limit · No legal mandate
What firms weigh
Hold USD when rate is high
Incentive
Risk · Early FX = FX loss
Exception · ADR·domestic capex needs
SK hynix ADR — policy meets capex
Real demand FX for domestic fabs, but split over 20–30 sessions (~$1B/day) to limit shock (Yonhap Infomax). Still a large USD supply event.
Other lenses
Exporters lose translation gains · SMEs/importers breathe · BOK faces growth vs FX trade-off · NPS swap/hedge is limited firepower · $350B U.S. investment is structural USD outflow risk.
Policy tools — relative short-term impact
FX policy tools short-term impact. Relative short-term (1–3M) contribution to stronger won. Author frame. Not guaranteed.
Broker H2 views
Hanwha Inv: 1,430–1,550 H2 · BNK Busan: Q4 avg 1,490 · KEA: ~1,480 in 3M, ~1,450 in 6–12M. Base story: gradual strengthening, not a crash.
H2 scenarios — four bands
Base 1,450–1,520 (45%) · Range 1,520–1,580 (30%) · Weak >1,580 (18%) · Strong <1,430 (7%).
Scenario levels — chart
H2 USD/KRW scenario bands. Midpoints of H2 2026 scenario bands. Blended from broker views + author frame. Not advice. · Axis starts at 1,300, not zero
Scenario probability — chart
H2 FX scenario probabilities. Author probability weights for H2 2026 main scenario. Sum 100%. Not advice.
Calendar checklist
ADR FX pace · foreign flows · U.S. CPI/Fed · Middle East/oil · U.S. investment execution · corporate USD deposit trend.
Wrap-up
Jul 8 was less ‘exports finally matter’ and more a $30B supply event pulled forward, plus govt jawboning. Structural dollar hoarding and U.S. investment outflows remain.
One line. The real test starts when the ADR conversion window ends.
Many cards to lower FX — but ammo and speeches are the ones actually played on hard days.
Sources
- Yonhap — USD/KRW below 1,500 Jul 8
- Kyunghyang — foreign buy & ADR
- Yonhap Infomax — SK hynix split FX
- Hankyung — ADR front-run
- Maeil — exporter FX SOS
- Maeil — daily FX monitoring
- Hanwha Inv — H2 FX outlook
- BNK Busan — Q4 1,490 view
- Yonhap — KEA 1,480/1,450
- Korea Times — structural paradox
- Internal: 2026-07-09-krw-1500-break-h2-outlook-session-01.md
For information only — this is not a recommendation to buy or sell any asset.
Comments 0