유로존 물가 3.8%, 에너지 18.8% 급등 — 한국 기업 이익은 왜 갈릴까Eurozone inflation hits 3.8% as energy jumps 18.8%: why Korean profits may diverge
유로존 물가가 다시 뛰었습니다. 10월 2일 Eurostat가 발표한 9월 소비자물가 속보는 전년 대비 3.8%입니다. 8월 확정치 3.2%보다 높습니다. 유럽에 물건을 파는 한국 기업에는 기회와 부담이 함께 생깁니다. 경쟁사의 에너지 비용이 올라 가격 경쟁은 쉬워질 수 있지만, 그 물건을 살 유럽 고객의 여력은 줄어들기 때문입니다. 출처: Eurostat 9월 속보
Eurozone inflation accelerated to 3.8% in September, from August’s final 3.2%, according to Eurostat’s October 2 flash release. Korean exporters face two competing forces: higher costs for European rivals may improve their relative prices, while weaker customer purchasing power may reduce orders. Source: Eurostat flash release
근데 이번 숫자를 소비가 너무 뜨거워졌다는 신호로만 읽으면 중요한 부분을 놓칩니다. 출발점은 에너지입니다. 관건은 비싼 연료가 어디까지 다른 가격을 끌어올리는지, 그리고 기업이 그 비용을 고객에게 얼마나 넘길 수 있는지입니다. 아래 업종·환율 영향은 이 경로를 바탕으로 한 조건부 분석이며 개별 종목의 매매 추천은 아닙니다.
유로존 물가 3.8%, 무엇이 올랐나
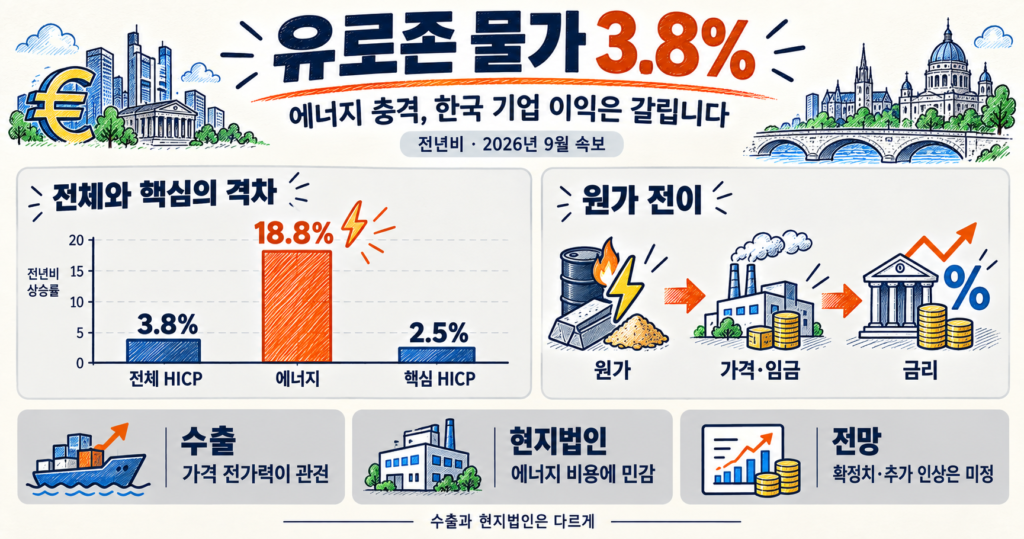
HICP는 나라별 소비자물가를 같은 기준으로 비교하는 조화소비자물가지수입니다. 9월 에너지 상승률은 전년 대비 18.8%로, 8월 14.3%보다 높아졌습니다. 반면 핵심물가는 2.4%에서 2.5%로 소폭 올랐습니다. 여기서 핵심물가는 에너지뿐 아니라 식품·주류·담배까지 제외한 지표입니다. 출처: Eurostat 구성표
9월 물가 속보: 전체·에너지·핵심. Eurostat, 2026-10-02. 각 지표의 상승률이며 전체 물가 기여도가 아닙니다. 핵심은 에너지·식품·주류·담배 제외.
18.8%는 에너지가 전체 물가를 18.8%포인트 끌어올렸다는 뜻이 아닙니다. 에너지 품목 자체의 1년 전 대비 가격 변화입니다. 전체 물가에 미친 기여도를 계산하려면 품목 비중과 지수 계산방식을 함께 봐야 합니다. 또한 에너지·미가공식품만 제외한 별도 지표는 2.2%입니다. 제외하는 품목이 달라 두 수치를 같은 핵심물가로 비교하면 안 됩니다.
속보는 추가 자료에 따라 바뀔 수 있습니다. 실제로 8월 전체 물가는 처음 3.3%로 발표됐다가 3.2%로 수정됐습니다. 이번 비교에는 최신 확정치를 사용했습니다. 월별 수치를 읽을 때는 발표 시점도 함께 맞춰야 합니다. 출처: 8월 확정 발표
비싼 에너지가 임금과 제품 가격으로 옮겨 가는 과정
유럽 기업이 수입 에너지를 더 비싸게 사면 같은 양을 생산해도 비용이 늘어납니다. ECB의 9월 1일 분석은 올해 5월까지의 물가 상승을 주로 에너지 공급 충격으로 설명합니다. 이 분석을 9월 상승분의 정확한 분해표로 볼 수는 없지만, 수요 과열과 다른 출발점을 이해하는 데 도움이 됩니다. 출처: ECB 분석
전달 속도는 계약마다 다릅니다. 전력·가스를 장기로 고정 구매한 공장은 당장 청구서가 덜 오를 수 있습니다. 현물 가격에 가까운 조건으로 사는 공장은 비용을 먼저 떠안습니다. 판매가격도 고정돼 있다면 이익률이 줄고, 계약을 새로 맺을 때 가격을 올릴 수 있다면 고객이 부담을 나눠 지게 됩니다. 소비자 에너지 지수와 공장 전기료가 같은 비율로 움직인다고 가정해서는 안 됩니다.
-
1
수입 비용
원자재 가격·유로 환율
-
2
기업 원가
계약 갱신 때 반영
-
3
가격·임금
가격 전가와 보전 요구
-
4
소비·투자
구매력·이자 부담 변화
환율은 이 청구서의 크기를 다시 바꿉니다. 달러 표시 에너지 가격이 같아도 유로가 달러에 약해지면 유로로 내는 수입 대금이 늘어납니다. 유로가 강해지면 반대입니다. 다만 금리 인상 기대만으로 유로 강세를 단정할 수는 없습니다. 에너지 수입 부담과 경기 불안은 유로를 약하게 만드는 힘이 될 수도 있습니다.
그다음은 임금입니다. 생활비가 오르면 근로자는 다음 임금 협상에서 보전을 요구할 수 있습니다. 기업이 임금 인상분까지 판매가격에 반영하면 에너지에서 시작한 상승이 오래 이어집니다. 그러나 이는 가능성입니다. 주문이 부족한 기업은 값을 올리는 대신 이익을 줄이거나 채용·투자를 미룰 수 있습니다. 핵심물가 2.5%만으로 임금과 가격이 서로 끌어올리는 순환이 이미 시작됐다고 결론 내릴 수는 없습니다.
핵심물가는 2.5%인데, ECB는 왜 경계를 풀지 않나
크리스틴 라가르드 ECB 총재는 9월 10일 기자회견에서 0.25%포인트 금리 인상 결정을 설명하면서도 향후 금리 경로를 미리 약속하지 않았습니다. 이미 다룬 관련: ECB의 직전 금리 인상 뒤에 이번 물가 속보가 새 판단 자료로 더해진 셈입니다. 금리는 원유 공급을 늘릴 수 없지만, 차입·소비·투자와 가격 인상 기대에는 영향을 줄 수 있습니다. 출처: ECB 기자회견
이자벨 슈나벨 ECB 집행이사는 9월 30일 연설에서 간접 효과와 2차 파급이 실제로 나타날 때까지 기다릴 수는 없다고 설명했습니다. 에너지 비용이 다른 상품 가격으로 퍼지는 것이 간접 효과이고, 임금·기대물가를 거쳐 다시 가격을 올리는 것이 2차 파급입니다. 지금 핵심물가가 전체 물가보다 낮다는 사실만으로 ECB의 추가 대응 가능성을 지울 수 없는 이유입니다. 출처: 슈나벨 연설
반대 방향의 힘도 있습니다. 크리스탈리나 게오르기에바 IMF 총재는 9월 7일 연설에서 에너지 충격의 지속성을 경계하면서도, 유럽의 2022년 가스 충격보다 가격 충격이 작고 경제의 여유 생산능력이 더 클 수 있다고 설명했습니다. 수요가 약하면 기업이 비용을 전부 넘기기 어렵습니다. ECB가 가격 전이를 경계하고 IMF가 그 전이를 제한할 조건을 함께 보는 이유가 여기에 있습니다. 출처: IMF 연설
따라서 추가 인상은 전망의 영역입니다. 에너지 고가가 길어지고 임금·서비스 가격까지 강해지면 인상 압력이 커질 수 있습니다. 반대로 주문과 고용이 약해지고 기대물가가 안정적이라면 ECB는 경기 부담을 더 무겁게 볼 수 있습니다. 공급 충격에 금리 부담까지 겹칠 때는 물가를 잡는 속도와 경기를 지키는 비용이 함께 문제가 됩니다.
한국 화학·철강·기계, 유럽 경쟁사가 힘들면 이익일까
한국에서 생산해 유럽으로 수출하는 기업은 유럽 경쟁사보다 원가 상승폭이 작을 때 가격 경쟁력이 좋아질 수 있습니다. 화학은 에너지를 연료뿐 아니라 원료로도 사용하므로 제품 판매가격과 원료비의 차이가 중요합니다. 유럽 공장의 가동 축소로 주문이 넘어오더라도 한국의 원료비와 운송비가 더 빨리 오르면 남는 이익은 줄 수 있습니다. 이는 업종별 가능성이지 확인된 수주 증가가 아닙니다.
철강도 유럽의 전력·가스 비용만 비교해서는 부족합니다. 생산방식마다 전력·석탄·가스 사용 비중이 다르고, 고객인 자동차·건설업의 구매량도 중요합니다. 경쟁사의 생산비가 올라도 유럽 전체 주문이 줄면 수출 물량을 늘리기 어렵습니다. 실제 계약에서는 운임, 제품 규격, 통관 비용과 적용되는 무역 조치까지 반영한 도착 가격을 비교해야 합니다.
기계는 조금 다른 갈림길에 있습니다. 고객이 공장 증설을 미루면 일반 설비 주문은 약해질 수 있습니다. 반면 에너지를 덜 쓰는 장비는 절감액이 커져 교체 투자 명분이 강해질 수 있습니다. 그래도 자금 조달 금리가 오르면 투자에 요구하는 수익률이 높아집니다. 전기료를 아끼는 효과가 커졌다는 이유만으로 발주가 확정되는 것은 아닙니다.
한국 생산·EU 수출
경쟁사보다 원가 상승이 작을 때
기회
부담 · 유럽 주문 감소·물류비
유럽 현지법인
현지 에너지·임금 부담
원가
환율 · 매출·원료·차입 통화 확인
유럽 현지법인은 수출기업과 사정이 다릅니다. 유로 매출과 유로 임금이 함께 있는 공장은 환율 변동 일부를 자연스럽게 상쇄할 수 있지만, 현지 에너지 가격 상승은 그대로 부담입니다. 달러로 원료를 사고 유로로 제품을 팔면 유로 약세에 더 취약해질 수 있습니다. 유로가 원화에 강해져 연결 매출의 원화 환산액이 늘어도 현지 영업이익률이 개선됐다는 뜻은 아닙니다.
소비자에게 보이는 에너지 요금과 기업이 내는 원가도 구분해야 합니다. 정부 지원이 가계 요금을 누르더라도 모든 공장의 구매가격까지 낮아지는 것은 아닙니다. 앞서 살펴본 관련: 에너지 지원 방식과 기업 현금흐름이 이번 물가 해석에도 연결됩니다. 실적을 볼 때는 판매량·판매단가·원가를 따로 확인해야 합니다.
가계 지갑과 자산시장, 미국은 공포·한국은 탐욕
가계는 난방·교통비를 먼저 내고 남은 돈으로 외식이나 내구재를 삽니다. 에너지 비용이 늘면 다른 소비에 쓸 실질 구매력이 줄 수 있습니다. 기업은 재고를 채우는 데 더 많은 자금이 필요해집니다. 여기에 금리까지 오르면 같은 매출을 유지하는 데 드는 금융비용도 커집니다. 매출 증가와 현금흐름 개선이 따로 움직일 수 있는 구조입니다.
자산시장에서는 두 경로가 겹칩니다. 인상 기대가 강해지면 채권 가격과 미래 이익의 현재 가치에 부담이 될 수 있습니다. 동시에 경기 둔화가 심해지면 기업 이익 전망도 약해집니다. 반대로 에너지 가격이 안정되면 이 두 부담이 줄 가능성이 있습니다. 이번 물가 발표만으로 유럽 채권·주식·유로의 실제 당일 방향을 단정하지 않는 이유입니다.
제공된 시장 스냅샷에서 CNN 미국 공포·탐욕지수는 10월 2일 31.1로 공포입니다. 1주 전 36.9, 1개월 전 46.1에서 각각 5.9·15.0포인트 낮아졌습니다. 한국 GoldKimp 코스피 지수는 10월 1일 60.5로 탐욕입니다. 산식과 기준일이 달라 점수 차이를 정밀 비교할 수는 없지만, 위험을 받아들이는 분위기는 다릅니다. 한국의 동일 방식 과거 점수가 없어 주간·월간 상승 여부는 판단하지 않았습니다. 출처: CNN 출처: GoldKimp
SentimenTrader 홈페이지에서는 최신 Smart Money·Dumb Money 수치가 공개되지 않았습니다. 공개 게시물 미러에서 확인한 최신 값은 9월 24일 Smart Money 0.41, Dumb Money 0.35입니다. 각각 41%·35%에 해당하며, 10월 2일 값은 아닙니다. 이 모델은 실제 기관·개인 자금 유입액이 아니므로 미국의 공포와 한국의 탐욕을 곧바로 자금 이동으로 해석할 수 없습니다. 유럽발 원가·금리 부담을 한국 시장의 낙관이 얼마나 견딜지는 결국 기업의 마진과 주문이 확인해 줘야 합니다. 출처: SentimenTrader 출처: 날짜가 표시된 공개 게시물 미러
10월 16일 확정치 이후, 한국 기업이 확인할 조건
아일랜드 통계청 CSO가 안내한 유로존 9월 HICP 확정치 발표 예정일은 10월 16일입니다. 아직 나오지 않은 확정치를 속보와 같은 값이라고 가정해서는 안 됩니다. 발표 때에는 수정 여부와 세부 기여도를 확인하고, 이후에는 기업의 가격 인상 계획·임금 협상·에너지 구매 계약을 함께 봐야 합니다. 출처: CSO 발표 일정
한국 기업에도 질문은 구체적입니다. 유럽 고객이 주문량을 유지하는지, 원가 상승분을 새 계약에 반영할 수 있는지, 에너지 절감 설비의 투자비를 고객이 조달할 수 있는지입니다. 이번 유로존 물가 상승은 유럽 경쟁사의 비용을 높이지만, 한국 기업의 이익을 보장하지는 않습니다. 가격 경쟁에서 얻은 몫이 수요 감소와 금융비용으로 얼마나 빠져나가는지가 다음 실적의 차이를 만들 것입니다.
유럽 경쟁사의 원가 상승이 한국 기업의 이익 증가를 보장하지는 않습니다.
출처
- Eurostat — September 2026 HICP flash estimate, 2 October
- Eurostat — August 2026 HICP final release, 17 September
- ECB — Christine Lagarde monetary policy statement, 10 September 2026
- ECB — Isabel Schnabel, Monetary policy in a world of overlapping shocks, 30 September 2026
- ECB Blog — Why the drivers of inflation matter for monetary policy, 1 September 2026
- IMF — Kristalina Georgieva, Monetary Policy with Supply Shocks and High Debt, 7 September 2026
- Ireland CSO — September HICP flash statement and final-release schedule, 1 October 2026
- CNN Fear & Greed — supplied pipeline snapshot, 2 October 2026
- GoldKimp KOSPI sentiment — supplied pipeline snapshot, 1 October 2026
- SentimenTrader — official homepage (current values not publicly visible)
- SentimenTrader public post mirrored by TwStalker — 24 September 2026 readings
The starting point is energy, rather than proof of an economy-wide demand boom. The crucial questions are how far expensive fuel spreads through other prices and how much of the bill firms can pass to customers. The sector and currency discussion below is conditional analysis, not a stock recommendation.
What sits inside eurozone inflation of 3.8%?
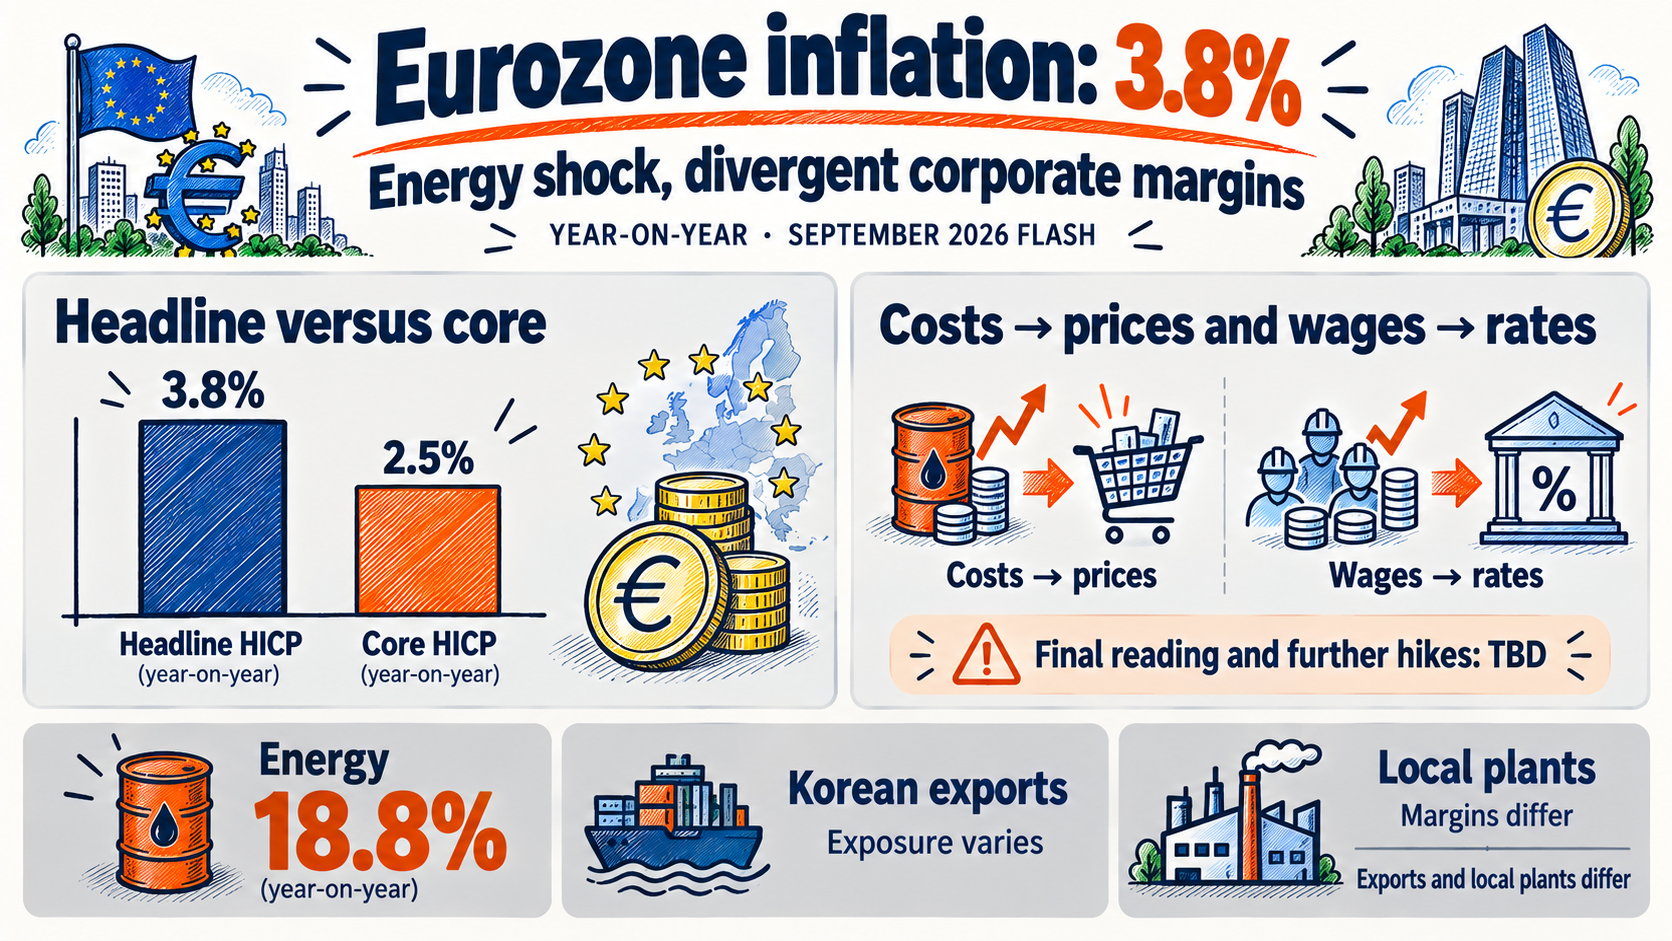
HICP is the harmonised consumer-price index used for comparable inflation measures across countries. Annual energy inflation rose from 14.3% to 18.8%. Core inflation, excluding energy, food, alcohol and tobacco, edged up from 2.4% to 2.5%. Source: Eurostat component table
September flash: headline, energy and core. Eurostat, Oct 2, 2026. Rates, not contributions. Core excludes energy, food, alcohol and tobacco.
An 18.8% energy reading is not an 18.8-percentage-point contribution to total inflation. It measures energy prices against a year earlier. Contributions require expenditure weights and the index methodology. A separate exclusion measure, removing only energy and unprocessed food, is 2.2%; it is not the same core series.
Flash figures can be revised: August was initially reported at 3.3% and later finalised at 3.2%. This comparison uses the revised figure, rather than mixing different release vintages. Source: August final release
How an energy bill reaches wages and selling prices
An imported-energy shock raises the cost of producing the same output. A September 1 ECB analysis attributed the rise through May mainly to adverse energy supply shocks. It helps identify the mechanism, but is not a decomposition of September’s increase. Source: ECB analysis
Timing depends on contracts. A plant with fixed-price energy procurement may be temporarily insulated. A buyer exposed to spot prices pays sooner. If selling prices are also fixed, margins absorb the shock; contract renewals may allow customers to share it. Consumer energy inflation is not a direct measure of industrial electricity costs.
-
1
Import bill
Commodity prices and euro exchange rate
-
2
Operating costs
Repricing at contract renewal
-
3
Prices and wages
Pass-through and wage claims
-
4
Spending and investment
Purchasing power and financing costs
Currency movements alter the bill again. With dollar energy prices unchanged, a weaker euro raises the euro cost of imports; a stronger euro reduces it. Expected rate increases do not guarantee euro appreciation, because deteriorating growth and a larger energy import bill can work in the opposite direction.
Workers may seek compensation for lost purchasing power in later wage negotiations. If employers then raise selling prices, the original shock becomes more persistent. That outcome is not automatic: weak orders may instead squeeze profits and delay hiring or investment. A 2.5% core reading alone does not establish a wage-price spiral.
Core is only 2.5%, so why is the ECB still wary?
On September 10, ECB President Christine Lagarde explained a 25-basis-point increase while refusing to pre-commit to a future rate path. September’s inflation release adds new information after the Related: previous ECB decision. Interest rates cannot produce more oil, but can influence borrowing, spending and expectations. Source: ECB press conference
ECB Executive Board member Isabel Schnabel argued on September 30 that monetary policy cannot simply wait for indirect and second-round effects to materialise. The former include higher input costs reaching other goods; the latter involve wages and expectations. Low core inflation relative to the headline therefore does not eliminate the possibility of further action. Source: Schnabel speech
IMF Managing Director Kristalina Georgieva warned on September 7 about the shock’s persistence, while noting a less extreme price shift than Europe’s 2022 gas shock and potentially more economic slack. Weak demand can constrain pass-through. These are conditions that may limit the process the ECB is watching. Source: IMF speech
Further tightening remains a scenario. Persistent energy costs alongside firmer wages and services prices would strengthen the case. Weaker orders and employment with stable inflation expectations could increase the weight given to growth. Policy has to judge both the inflation risk and the cost of suppressing demand.
Do higher European costs help Korean exporters?
A Korean producer gains relative price competitiveness only if its own costs rise less than those of European rivals. Chemicals use energy as both fuel and feedstock, making the product-feedstock spread important. Even displaced European orders may deliver less profit if Korean input and shipping costs rise faster. This is a mechanism, not a claim of observed order gains.
For steel, the relevant energy mix varies by production process. Demand from automotive and construction customers matters as much as a competitor’s electricity bill. Compare delivered prices, including freight, specifications, customs costs and applicable trade measures; higher rival costs do not guarantee more volume in a shrinking market.
Machinery faces a different split. Expansion projects may be delayed, while energy-saving equipment becomes more valuable. Yet higher financing costs raise the return a customer requires from a project. Better energy savings alone do not secure a purchase order.
Korean production, EU exports
Smaller cost increase than rivals
Opportunity
Risk · Weaker orders and freight costs
European subsidiary
Local energy and wages
Costs
Currency · Match revenue, input and debt currencies
A European subsidiary has a different exposure. Euro revenues and euro wages provide a partial natural currency offset, but do not remove local energy inflation. Dollar inputs against euro sales can create additional vulnerability. A stronger euro against the won may boost translated revenue without improving the plant’s operating margin.
Household energy tariffs and industrial procurement costs also differ. Support that lowers a household bill may not reduce every factory’s costs. This connects to our earlier discussion of Related: energy support and corporate cash flow. Earnings analysis needs separate checks on volumes, selling prices and costs.
Household budgets, asset markets, and fear in the US versus greed in Korea
Households pay heating and transport bills before many discretionary purchases. More expensive energy can reduce the purchasing power available for other goods. Businesses also need more working capital to replenish inventories. If rates rise, maintaining the same sales level can cost more to finance, separating revenue growth from cash-flow improvement.
Assets face both a financing channel and an earnings channel. Higher expected rates can weigh on bond prices and the present value of future profits, while weaker activity can reduce those profits. Energy stabilisation could ease both pressures. None of this establishes the actual market reaction on release day.
The supplied snapshot puts CNN’s US Fear & Greed Index at 31.1, fear, on October 2—down 5.9 points from a week earlier and 15.0 from a month earlier. GoldKimp’s KOSPI reading was 60.5, greed, on October 1. Different methods and dates prevent a precise score comparison. Comparable Korean weekly and monthly history was unavailable. Source: CNN Source: GoldKimp
SentimenTrader’s homepage did not expose current Smart/Dumb Money readings. The latest visible dated public-post mirror showed 0.41 and 0.35, equivalent to 41% and 35%, on September 24—not October 2. These models are not actual institutional and retail cash flows. Whether Korean optimism can withstand European cost and rate pressure depends on orders and margins. Source: SentimenTrader Source: Dated public-post mirror
After the October 16 final data: what Korean firms should check
Ireland’s CSO lists October 16 as the scheduled release of the final September eurozone HICP. It has not yet been published. Check revisions and detailed contributions, then monitor pricing plans, wage negotiations and energy procurement contracts. Source: CSO release schedule
For Korean companies, ask whether European customers maintain volumes, whether new contracts recover higher costs, and whether buyers can finance efficiency projects. Relative price gains can be offset by weaker demand and financing expenses. That balance, rather than inflation alone, will shape the next earnings reports.
Higher costs for European rivals do not guarantee higher profits for Korean firms.
Sources
- Eurostat — September 2026 HICP flash estimate, 2 October
- Eurostat — August 2026 HICP final release, 17 September
- ECB — Christine Lagarde monetary policy statement, 10 September 2026
- ECB — Isabel Schnabel, Monetary policy in a world of overlapping shocks, 30 September 2026
- ECB Blog — Why the drivers of inflation matter for monetary policy, 1 September 2026
- IMF — Kristalina Georgieva, Monetary Policy with Supply Shocks and High Debt, 7 September 2026
- Ireland CSO — September HICP flash statement and final-release schedule, 1 October 2026
- CNN Fear & Greed — supplied pipeline snapshot, 2 October 2026
- GoldKimp KOSPI sentiment — supplied pipeline snapshot, 1 October 2026
- SentimenTrader — official homepage (current values not publicly visible)
- SentimenTrader public post mirrored by TwStalker — 24 September 2026 readings
이 글은 정보 제공 목적이며, 특정 자산의 매수·매도를 권유하지 않습니다.
For information only — this is not a recommendation to buy or sell any asset.
댓글Comments 0