미국 소비 0.6% 증가, 실질소득은 제자리 — 이 소비 얼마나 갈까US consumption rose 0.6%, real income stalled — how long can spending last?
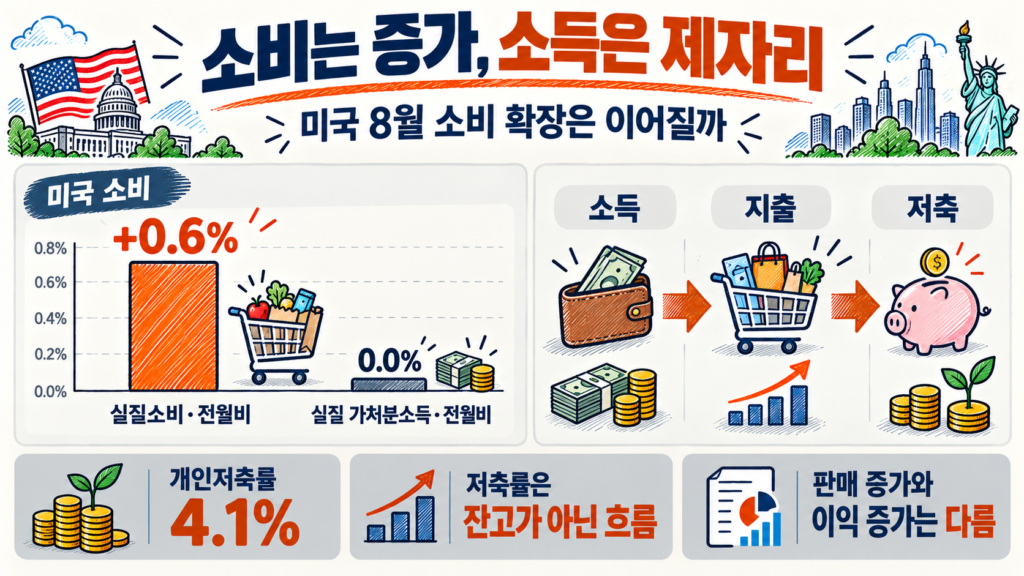
미국 소비는 늘었는데, 물가를 빼고 계산한 소득은 제자리였습니다. 미국 경제분석국(BEA)이 9월 30일 발표한 8월 통계에서 실질소비는 전월보다 0.6% 늘고 실질 가처분소득은 변화가 없었습니다(0.0%). 개인저축률은 4.1%였습니다. 판매는 활발해졌지만, 이를 계속 뒷받침할 구매력이 함께 커졌는지는 별개의 문제입니다. 출처: 원자료
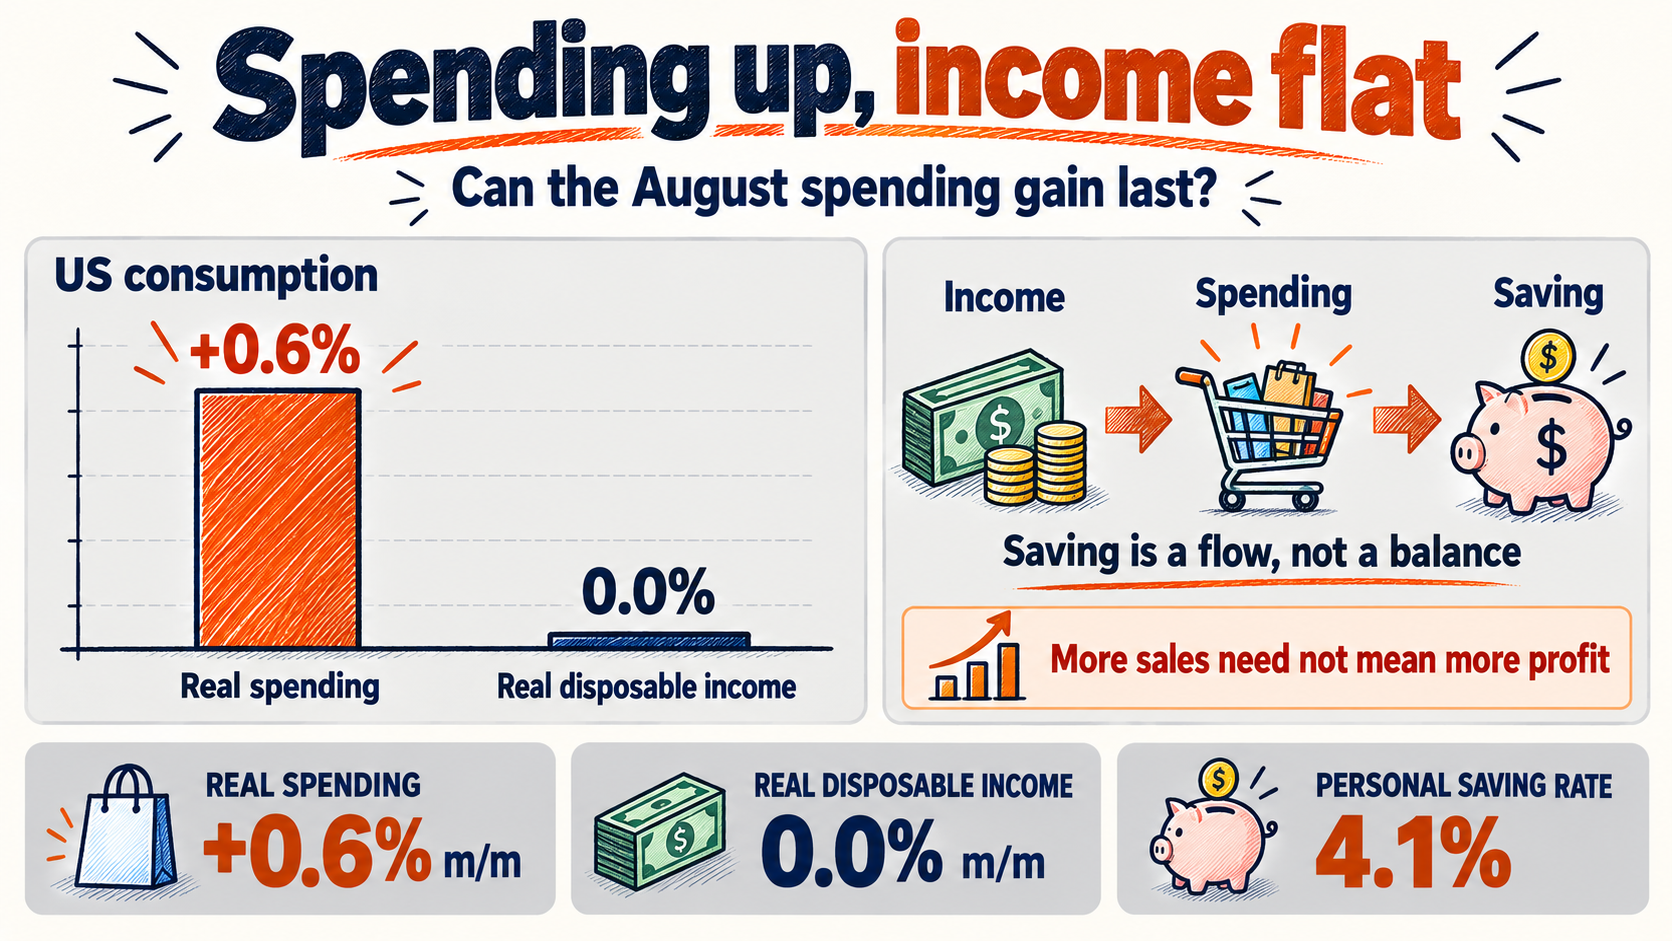
US consumption rose in August, but inflation-adjusted disposable income did not. The BEA’s September 30 release reported real spending up 0.6% from July, flat real disposable income and a 4.1% saving rate. Stronger sales and stronger spending capacity are different things. Source: Source
한국 자동차·가전 기업에는 반가운 수요 신호입니다. 다만 소비자가 할인이나 할부 지원을 받아 물건을 샀다면 판매 증가가 이익 증가로 고스란히 이어지지는 않습니다. 그럼 이 소비, 어디서 나온 돈일까요? 이번 숫자는 미국 소비가 무너졌다는 증거도, 내구재 호황이 계속된다는 보증도 아닙니다.
미국 소비 0.6%, 소득 0.0%를 함께 읽어야 하는 이유
가처분소득은 세금을 내고 남은 소득입니다. 여기서 물가 상승의 영향을 제거한 값이 실질 가처분소득입니다. 이번 달 명목 가처분소득은 0.3% 늘었지만 PCE 물가지수도 전월보다 0.3% 올라, 반올림된 실질 증가율은 0.0%가 됐습니다. 들어오는 돈이 늘어도 살 수 있는 물건과 서비스의 양은 거의 늘지 않았다는 뜻입니다. 출처: 원자료
소비는 달랐습니다. 가격 효과를 뺀 실질소비가 0.6% 늘었습니다. 아래 그림은 같은 달의 전월비 증가율만 비교합니다. 저축률 4.1%는 소득 중 저축의 비중이므로 이 막대들과 같은 종류의 증가율로 비교하면 안 됩니다.
8월 구매력과 소비의 간격. BEA, 2026-09-30. 실질소득은 실질 가처분소득. 저축률 4.1%와 단위가 다릅니다.
개인소득 증가에는 보수와 정부 사회급여가 기여했습니다. 그렇다고 모든 가구의 월급이 같은 폭으로 오른 것은 아닙니다. 전체 평균에는 임금뿐 아니라 여러 소득원이 섞여 있고, 돈을 더 번 가구와 소비를 더 늘린 가구가 서로 다를 수도 있습니다. 출처: 원자료
저축률 4.1%는 통장에 남은 돈이 아닙니다
저축률은 일정 기간의 소득에서 지출을 빼고 얼마가 남았는지 보여줍니다. BEA의 개인지출에는 소비 외에 개인 이자지급과 경상이전도 들어갑니다. 따라서 저축률을 단순히 “100에서 소비 비중을 뺀 값”으로만 계산하면 정확하지 않습니다. 출처: 원자료
이 비율이 양수라는 것은 전체적으로 그 기간에 저축이 발생했다는 뜻입니다. 모든 가구가 예금을 인출했다는 뜻은 아닙니다. 누군가는 매달 저축하던 금액을 줄이고, 다른 가구는 보유 자산을 팔거나 대출을 이용할 수 있습니다. 이번 총량 통계만으로 어느 경로가 소비 증가를 얼마나 설명했는지는 알 수 없습니다.
가령 물가가 일정하고 이자 등 다른 지출이 없다고 가정해 보겠습니다. 한 달 소득 100에서 소비 95, 저축 5였던 가구가 소비를 96으로 늘리면 저축은 4가 됩니다. 소득이 늘지 않아도 소비는 증가할 수 있습니다. 다만 같은 방법을 계속 쓰려면 저축할 여지가 충분해야 합니다.
-
1
소득 100 유지
물가 일정·기타 지출 없음
-
2
저축 5 → 4
그달 새로 저축하는 금액 감소
-
3
소비 95 → 96
예금 인출 없이도 가능
그래서 앞으로 중요한 것은 저축률의 높고 낮음만이 아닙니다. 실질 소득이 다시 늘어 소비를 따라잡는지, 소비 증가가 일부 자산 보유 가구에 집중되는지, 일자리가 흔들릴 때 지출을 유지할 여유가 있는지를 함께 봐야 합니다. 한 달의 격차를 바로 소비 위기로 해석하기에는 정보가 부족합니다.
주가는 소비를 밀고, 금리는 당깁니다 — 월러와 FOMC의 엇갈린 신호
크리스토퍼 월러 연준 이사는 9월 3일 연설에서 주가 상승으로 늘어난 부가 소비 성장을 지탱할 것으로 봤습니다. 주식 평가액이 오르면 소득이 당장 늘지 않아도 큰 지출을 감당할 수 있다고 느낄 수 있습니다. 다만 주식을 적게 가진 가구까지 같은 효과를 누리지는 않습니다. 출처: 원자료
월러는 물가 개선이 이어지는지에 따라 금리 판단이 달라질 수 있다고 덧붙였습니다. 약 2주 뒤 연준 FOMC는 9월 16일 내수가 견조하고 물가가 높다고 평가하며 정책금리 목표범위를 0.25%포인트 올려 3.75~4.00%로 정했습니다. 금리가 높아지면 신규 할부 비용이 늘 수 있지만, 실제 대출금리는 신용도와 만기, 금융사 경쟁에도 달려 있습니다. 출처: 원자료
주식시장도 소비 증가를 곧바로 낙관하고 있지는 않습니다. 10월 1일 기준 CNN 공포·탐욕 지수는 28.1로 ‘공포’ 구간입니다. 1주 전 35.7보다 7.7포인트, 1개월 전 44.9보다 16.8포인트 낮습니다. 자산 효과를 기대하더라도 투자심리 약화가 이어지면 큰 구매를 미룰 수 있다는 점은 고려해야 합니다. 이 지수만으로 실제 소비 감소를 예측할 수는 없습니다. 출처: 원자료
한국은 GoldKimp의 9월 30일 KOSPI 지수가 59.3으로 탐욕에 해당합니다. 미국과 심리 방향이 다르지만 산식이 달라 점수 차이를 그대로 비교할 수는 없습니다. 다만 한국 지수는 현재 자료에 주·월 비교치가 없어 방향까지 말하긴 어렵습니다. 미국 소비 둔화를 걱정하는 시각과 달리 국내 증시 심리는 탐욕 쪽이라, 미국 수요에 기대는 자동차·가전주의 기대치가 실적보다 앞서 갈 수 있다는 점은 염두에 둘 만합니다. 스마트머니·덤머니 지표(SentimenTrader)는 10월 2일 기준 공개 페이지에 최신 수치와 기준일이 표시되지 않았습니다. 출처: 원자료
현대차 판매는 줄었는데 하이브리드는 33% 증가 — 자동차·가전은 이익을 봐야 합니다
현대차의 회사 발표가 좋은 사례입니다. 9월 1일 공개한 8월 미국 판매는 8만6,977대로 전년보다 2% 줄었지만 하이브리드는 33% 늘었습니다. 랜디 파커 북미 사장 겸 CEO는 하이브리드 수요 강세와 함께 지난해 전기차 선구매, 노동절 시점의 비교 영향을 설명했습니다. 전체 수요 숫자 하나로 모든 차종의 판매를 설명할 수 없는 이유입니다. 출처: 원자료
현대차 판매는 전년비 대수이고 BEA 소비는 전월비 실질 금액입니다. 두 증가율을 같은 기준으로 비교할 수는 없습니다. 다만 제품 구성과 비교 시점이 중요하다는 점은 확인할 수 있습니다. 현대차·기아의 향후 실적을 볼 때에는 판매대수뿐 아니라 대당 할인, 저금리 할부 지원비, 재고가 얼마나 오래 남는지도 살펴야 합니다.
예를 들어 판매가격을 낮춰 주문을 확보하면 공장 가동률은 지킬 수 있습니다. 하지만 부품비와 인건비가 그대로라면 대당 이익은 줄어듭니다. 반대로 할인 없이 잘 팔리는 차종이 늘면 전체 판매가 빠르게 늘지 않아도 수익성은 좋아질 수 있습니다. 실제 8월 이익이 어땠는지는 다음 실적 발표에서 확인해야 합니다.
가전도 비슷합니다. LG전자는 7월 30일 2분기 실적 발표에서 프리미엄과 보급형을 함께 공략하고 비용·공급망을 개선했다고 설명했습니다. 미국 관세 환급이라는 일회성 이익도 반영했습니다. 이 발표는 세계 사업 실적이므로 미국 소비 호조의 직접 증거로 쓰기는 어렵습니다. 오히려 가전 이익을 볼 때 수요, 제품 구성, 비용, 일회성 항목을 나눠 봐야 한다는 사례입니다. 출처: 원자료
소득 회복이 뒷받침
지속적인 구매 여력
소비자
기업 · 할인 부담 없이 판매 가능
투자 · 주문 반복 시 증설 근거
판촉·저축 축소에 의존
앞당긴 구매는 반복 어려움
소비자
기업 · 금융지원·할인 비용 부담
투자 · 재고·주문 지속성 확인 필요
냉장고·세탁기는 고장이 나면 교체해야 하지만, 아직 쓸 수 있다면 구매를 미룰 수 있습니다. 삼성전자·LG전자의 미국 판매에도 이런 차이가 중요합니다. 주택 거래와 입주가 늘면 새 가전 수요를 도울 수 있고, 주거비 부담이 크면 교체 예산이 줄 수 있습니다. 앞서 다룬 관련: 미국 주택 착공과 건설사 할인 흐름도 가전 수요의 지속성을 볼 때 함께 읽을 만합니다.
기업 투자 역시 한 달의 판매 증가만으로 크게 늘리기 어렵습니다. 주문이 반복되고 재고가 안정적으로 줄어야 생산능력을 늘릴 근거가 생깁니다. 현지 생산과 제품 구성을 조정할 수 있는 기업은 수요 변화에 대응하기 쉽지만, 전용 설비 비중이 큰 공급업체는 특정 차종·제품의 부진에 더 민감할 수 있습니다. 관련: 미국 연비 규제와 자동차·배터리 손익에서 본 비용 차이도 구매 여력과 함께 작용합니다.
소비가 이어지려면: 실질소득·내구재 비중·개정치
첫째는 실질 가처분소득입니다. 고용과 임금이 뒷받침되고 물가 상승이 완만해지면 저축을 더 줄이지 않고도 소비를 늘릴 수 있습니다. 반대로 생활필수품 가격이 소득보다 빠르게 오르면 자동차나 가전처럼 미룰 수 있는 구매가 압박받을 수 있습니다. 현재 소비 증가가 유지되느냐는 결국 이 구매력의 회복에 달려 있습니다.
둘째는 소비의 구성입니다. 서비스 지출 증가가 자동차·가전 판매 증가를 뜻하지는 않습니다. 실질 내구재 소비, 기업별 판매와 판촉비가 같은 방향을 가리키는지 봐야 합니다. 미국 판매가 늘어도 현지 생산 비중과 환율, 비용 구조에 따라 한국 수출이나 원화 이익에 미치는 영향은 달라집니다.
셋째는 여러 달의 흐름과 개정치입니다. 이번 BEA 발표에는 2021년 이후 계열의 연례 개정이 포함돼 있습니다. 과거 발표에서 가져온 숫자와 최신 숫자를 무심코 섞으면 추세를 잘못 읽을 수 있습니다. 다음 개인소득·지출 발표는 10월 29일 미국 동부시간 오전 8시 30분 예정입니다. 출처: 원자료
솔직히 “미국인이 얼마나 더 샀나”보다 중요한 질문은 그다음입니다. 같은 소비를 다음 달에도 감당할 소득이 늘고 있는지, 기업은 그 판매에서 이익을 남기는지입니다. 두 조건이 함께 좋아져야 소비 확장이 기업 투자와 고용으로 이어질 가능성도 높아집니다. 이 글은 경제 해설이며 특정 자산의 매수·매도 권유가 아닙니다.
소비를 이어 갈 소득과 판매에서 남는 이익을 함께 확인해야 합니다.
출처
- BEA — Personal Income and Outlays, August 2026
- Federal Reserve — September FOMC statement
- Christopher Waller — Economic Outlook
- Hyundai Motor America — August 2026 Sales
- LG Electronics — Second-Quarter 2026 Results
- CNN Fear & Greed
- GoldKimp KOSPI Fear & Greed
- SentimenTrader — Smart/Dumb Money Confidence
For Korean car and appliance makers, stronger demand is welcome. But if discounts or subsidized financing enabled a purchase, additional sales may bring much less additional profit. So where did the money come from? This report establishes neither a consumer collapse nor a durable boom.
US consumption: why 0.6% spending and flat income belong together
Disposable income is income after personal taxes; real disposable income adjusts that amount for prices. Nominal disposable income rose 0.3%, alongside a 0.3% rise in the PCE price index. The rounded real change was therefore zero: more dollars did not buy meaningfully more goods and services. Source: Source
Spending behaved differently: it increased 0.6% even after adjusting for prices. The chart compares monthly real growth rates only. The 4.1% saving rate is a share of income, not another growth rate.
August income and spending growth. BEA, September 30. Income means disposable income. The saving rate uses a different denominator.
Compensation and government social benefits contributed to income growth. That does not mean every household received the same raise. Aggregate income combines multiple sources, and the households earning more need not be those spending more. Source: Source
A 4.1% saving rate is not a bank balance
The saving rate measures the share of income left after personal outlays during a period. BEA outlays include consumption, personal interest payments and current transfers. It is not simply 100 minus consumption’s share of income. Source: Source
A positive rate means aggregate saving remained positive during the period. It does not establish widespread withdrawals. Some households may save less each month, others may sell assets or borrow. This aggregate release does not identify how much each channel contributed.
Consider an illustration with stable prices and no other outlays. A household earning 100, spending 95 and saving 5 can raise spending to 96 by saving only 4. Income need not rise immediately. Repeating the adjustment, however, requires room to save less.
-
1
Income stays 100
Stable prices; no other outlays
-
2
Saving 5 → 4
Less new saving during the month
-
3
Spending 95 → 96
Possible without withdrawing deposits
The next question is whether real income catches up, whether spending strength is concentrated among asset owners, and whether households can withstand an employment setback. A single monthly gap is insufficient evidence of a consumption crisis.
Stocks push spending, rates pull back: Waller and the FOMC
In his September 3 speech, Fed Governor Christopher Waller expected higher equity wealth to support consumption. Wealth gains can make purchases feel more affordable without immediately increasing income; households with little equity exposure benefit less. Source: Source
Waller added that his rate decision would depend on continued progress on inflation. About two weeks later, on September 16, the FOMC raised its target range by 0.25 percentage points to 3.75–4.00%, citing resilient domestic spending and elevated inflation. New loan costs can rise, though pricing also depends on credit quality, maturity and lender competition. Source: Source
As of October 1, CNN’s Fear & Greed Index stood at 28.1, in the fear range, down 7.7 points from 35.7 a week earlier and 16.8 from 44.9 a month earlier. Persistent investor caution could temper large purchases supported by wealth. The index alone cannot predict a decline in consumption. Source: Source
GoldKimp’s September 30 KOSPI reading was 59.3, or greed. The mood differs from the US, but different methodologies prevent a direct numerical comparison. The available Korean data lack week- and month-earlier comparisons, so the direction is unclear. With Korean sentiment in greed despite concerns about US spending, expectations for car and appliance stocks exposed to US demand could run ahead of earnings. As of October 2, SentimenTrader’s public page displayed neither current Smart Money and Dumb Money readings nor their date. Source: Source
Hyundai sales fell, hybrids rose 33% — watch auto and appliance margins
Hyundai’s September 1 company release illustrates the distinction: August US sales were 86,977, down 2% year over year, while hybrids rose 33%. North America CEO Randy Parker cited hybrid demand and a difficult comparison involving earlier EV purchases and Labor Day timing. One demand headline cannot explain every vehicle segment. Source: Source
Hyundai reports year-over-year units; BEA reports month-over-month real expenditure. The growth rates are not directly comparable. The useful lesson is the importance of product mix and comparison periods. For Hyundai and Kia, watch discounts per vehicle, financing support and inventory duration alongside volume.
Discounting can protect factory utilization while reducing profit per vehicle if component and labor costs remain unchanged. A richer mix of vehicles sold without discounts can improve profitability even with modest volume growth. The next earnings release will help show how August sales translated into profit.
LG’s July 30 results described a premium-and-volume appliance strategy, cost and supply-chain improvements, and a one-time US tariff refund benefit. These are global results, not direct evidence of strong US household demand. They illustrate why appliance earnings should be separated into demand, product mix, costs and nonrecurring items. Source: Source
Supported by income
Recurring purchasing capacity
Consumer
Producer · Potential full-price sales
Investment · Repeat orders support capacity
Dependent on incentives
Pull-forward may not repeat
Consumer
Producer · Financing and discount costs
Investment · Need durable orders, lean stocks
A broken refrigerator may need immediate replacement; a working one can wait. That distinction matters for Samsung and LG in the US. Housing turnover and move-ins can support new appliance purchases, while housing costs can squeeze replacement budgets. Our earlier article on Related: US housing starts and builder discounts adds context.
Investment needs repeat orders and sustainable inventory reduction, not one strong sales month. Firms able to adjust local production and product mix have more flexibility; suppliers with dedicated equipment may be more exposed to a weak model or category. The cost differences discussed in our article on Related: US fuel-economy rules and auto/battery margins interact with affordability.
What keeps spending going: real income, durables mix, revisions
First, real disposable income. Employment and wage gains combined with slower price increases would allow spending to grow without further reducing saving. If essentials become more expensive faster than income grows, postponable purchases face pressure. Recovering purchasing power is central to durability.
Second, composition. Strong services spending does not guarantee stronger car or appliance sales. Compare real durable-goods spending with company sales and promotion costs. Local production, exchange rates and cost structures determine how US demand translates into Korean exports and won-denominated profit.
Third, several months of data on a consistent revision basis. This release incorporates annual revisions beginning in 2021. Mixing old-release figures with revised observations can distort the trend. The next personal income and outlays release is scheduled for October 29 at 8:30 a.m. Eastern time. Source: Source
The more useful question comes after how much Americans bought: is income growing enough to fund the next purchase, and are companies earning a margin on it? Improvement in both would give consumption a better chance of supporting investment and employment. This is economic analysis, not an investment recommendation.
Watch the income that sustains spending and the margin that sales leave behind.
Sources
- BEA — Personal Income and Outlays, August 2026
- Federal Reserve — September FOMC statement
- Christopher Waller — Economic Outlook
- Hyundai Motor America — August 2026 Sales
- LG Electronics — Second-Quarter 2026 Results
- CNN Fear & Greed
- GoldKimp KOSPI Fear & Greed
- SentimenTrader — Smart/Dumb Money Confidence
이 글은 정보 제공 목적이며, 특정 자산의 매수·매도를 권유하지 않습니다.
For information only — this is not a recommendation to buy or sell any asset.
댓글Comments 0