China Export Growth Hits 25% — How a $119 Billion Surplus Pressures Korean Industry
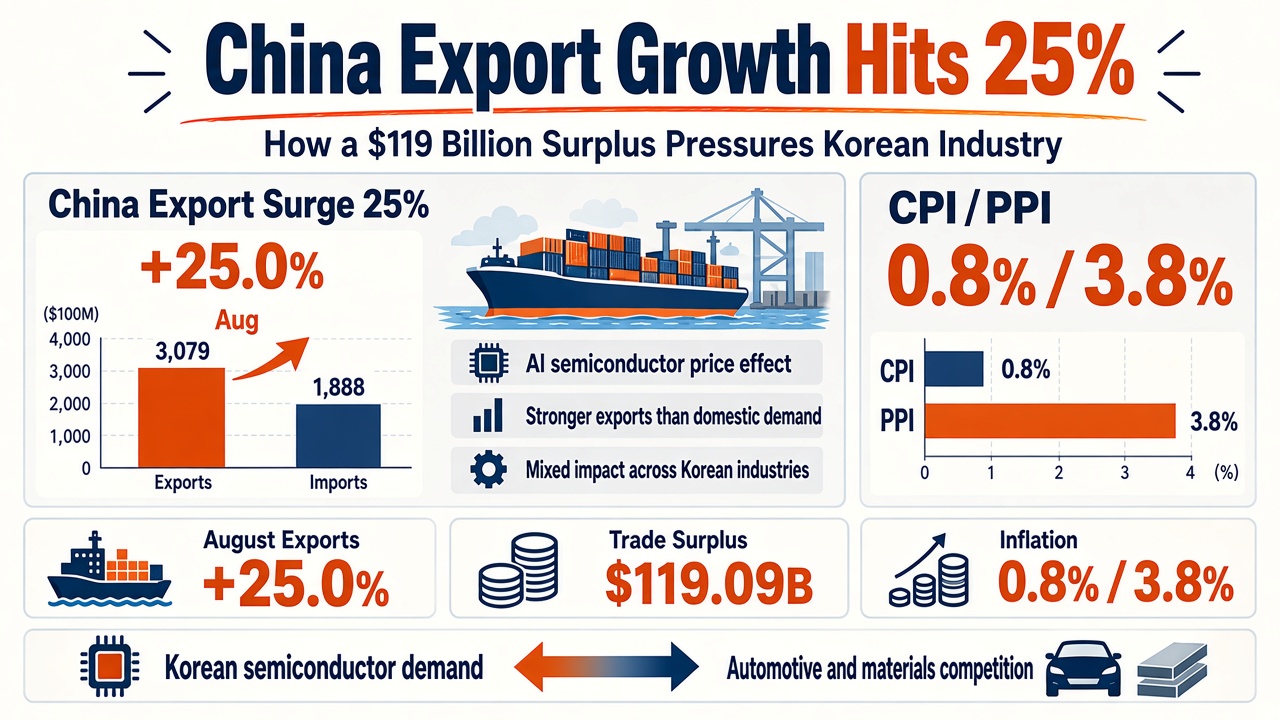
China export growth is changing global price competition again. Exports rose 25.0% year on year in August 2026 and the trade surplus widened to $119.09 billion. For Korea, that is both an opportunity for semiconductor demand and a warning that competition in autos, steel and chemicals may intensify.
Imports also rose 28.2%, which might suggest a broad domestic recovery. Yet consumer inflation was only 0.8%, while food prices fell 1.4%. Factories and trade are hot; the household shopping basket is not.
The statistics below are verified. Statements about future markets and earnings are scenarios, not investment recommendations.
What drove China’s 25% export surge?
In dollar terms, August exports were roughly $401.4 billion and imports about $282.4 billion. Imports grew faster in percentage terms, but exports started from a much larger base. The surplus therefore rose from $112.5 billion in July to $119.09 billion.
In yuan terms, goods trade reached 34.78 trillion yuan in January through August, up 17.6%. Exports were 20.17 trillion yuan and imports 14.61 trillion yuan. This was more than a one-month statistical accident. The product mix is crucial: auto export value rose 43%, while integrated-circuit exports jumped 129.8%. Caixin reported that chip export volume actually fell 8%. The 130% value increase therefore reflects a powerful price effect linked to AI-chip scarcity, not simply more physical output.
Comparison of China’s August export growth of 25% and import growth of 28.2%. Dollar terms. Trade surplus: $119.09B. · Axis starts at 23, not zero
Why did tariffs fail to stop the export machine?
China changed destinations. Exports to Southeast Asia rose 30.2%, Latin America 17.5% and the EU 6.6%. A tariff can redirect trade through new markets and production routes rather than eliminate it.
China also moved toward higher-value products. Autos, semiconductors and computing equipment now sit alongside traditional consumer goods. Years of manufacturing investment have expanded Chinese capabilities in automation, electric vehicles and technology.
Weak domestic demand is the other side of the story. A prolonged property downturn and a limited safety net encourage households to save. Producers then need foreign customers to absorb capacity. That is why the IMF recommends shifting resources from inefficient industrial support toward social protection, property adjustment and consumption.
-
1
Property slump and saving
Weak household demand
-
2
Industrial support and capex
More capacity
-
3
AI and auto exports
Foreign demand absorbs output
-
4
Large trade surplus
More trade friction
CPI at 0.8%, PPI at 3.8%: a two-speed economy
The consumer price index tracks what households buy. The producer price index tracks prices at the factory gate. In August, Chinese CPI rose 0.8%, while PPI increased 3.8%. Producer-goods prices climbed 5.0%, but consumer-goods prices at the factory gate fell 0.5%.
The gap suggests rising costs and prices in raw materials and export manufacturing are not passing evenly to Chinese households. When consumer demand is weak, firms have less pricing power at home. They may accept lower margins or push harder into overseas markets.
Consumer CPI +0.8%
Prices households pay
·
· · Food -1.4%
· · Domestic demand still mild
Producer PPI +3.8%
Factory-gate prices
·
· · Producer goods +5.0%
· · Raw-material and export pressure
Those are the confirmed numbers. Whether this pattern persists is a forecast. Stable energy costs and a property recovery could allow consumption to catch up. If domestic demand remains weak while production expands, more output may be pushed abroad and trade defenses may strengthen.
Korean semiconductors face demand and competition
More Chinese AI-server production can lift Korean memory demand. High-bandwidth memory, or HBM, sits next to AI processors and moves large datasets quickly. If China’s import boom includes equipment and components, Korean suppliers can gain revenue.
But the 129.8% jump in integrated-circuit export value also signals that China is becoming a larger semiconductor seller. The current gain is price-heavy, and technology gaps remain at the frontier.
That does not make the competitive pressure trivial. More Chinese supply in commodity memory, power chips and automotive semiconductors can pressure Korean pricing and market share.
Investors should therefore separate China revenue from shipment volume, average selling prices, inventory and Chinese capacity. As discussed in our analysis of AI investment and jobs, stronger sales do not automatically produce broader employment or investment.
Autos, steel and chemicals meet China in third markets
Korean automakers no longer compete with Chinese brands only inside China. A 43% rise in Chinese auto exports means more direct contests in Southeast Asia, Latin America and Europe. Korean firms may discount or spend more on battery efficiency, service networks and brand differentiation.
Steel and petrochemicals face a more direct risk. If Chinese construction and consumption remain soft, excess production can move abroad. Falling export prices pressure Korean selling prices. When raw-material costs rise at the same time, margins are squeezed from both sides.
Shipping may benefit from higher cargo volumes, but tariffs and anti-dumping cases can reroute trade and raise costs. Add the fuel burden described in our oil-price analysis, and higher freight rates do not automatically translate into higher profit.
Demand opportunity
HBM and advanced memory
·
· · AI power and equipment
· · Shipping volumes
Competitive pressure
Autos in third markets
·
· · Steel and chemical pricing
· · Commodity-chip supply
Cheaper goods, weaker paychecks — the Korean trade-off
More Chinese supply can lower prices for Korean consumers. But if it weakens domestic manufacturing sales and employment, household income suffers. Cheaper goods and weaker paychecks can arrive together.
Capital spending will diverge. AI memory and power equipment may retain orders, while commodity-material producers delay new plants if oversupply persists. Banks will care less about headline export growth than about borrower inventories and cash flow.
The won could move either way. Strong Chinese trade can support Asian export currencies, but escalating trade conflict or yuan depreciation can pull the won lower.
In equities, China exposure alone is a weak screen. Firms with pricing power and disciplined inventory management may command a premium over companies that merely report high China exposure.
Four numbers to watch next
First, separate export value from volume. A price surge can make semiconductor exports look stronger than physical production. Second, watch Chinese retail sales and housing transactions. Domestic recovery is necessary to reduce reliance on exports.
Third, compare Korea’s intermediate-goods exports to China with its finished-goods exports to Southeast Asia. Selling parts into Chinese factories and competing with Chinese finished products can happen simultaneously. Fourth, monitor tariffs and anti-dumping actions. A $119 billion monthly surplus raises the probability of policy responses.
China’s 25% export surge is not a simple recovery signal. It combines AI-related price inflation, market diversification and weak domestic absorption. For Korean investors, the better question is whether a company sells inputs to China’s factories or sells the same finished product against them. That distinction could shape the next earnings cycle.
What matters is not merely that China sold more, but whether a Korean company supplies Chinese factories or competes with their finished products.
Sources
- Reuters — China exports surge 25% in August
- China State Council / GAC — January–August goods trade
- Caixin Global — AI prices and chip export volume
- Associated Press — August destinations and products
- China NBS — August 2026 CPI
- China NBS — August 2026 PPI
- IMF — China’s pivot to consumption-led growth
- IMF Working Paper — Industrial policy and global imbalances
- WTO — 2026 global goods trade update
- 내부 글 — AI 투자와 고용의 엇갈림
- 내부 글 — 유가와 한국 기업 비용
For information only — this is not a recommendation to buy or sell any asset.
Comments 0