Bank of Korea Rate Hike — 2.50% to 2.75%, Won, Rate Gap & Housing
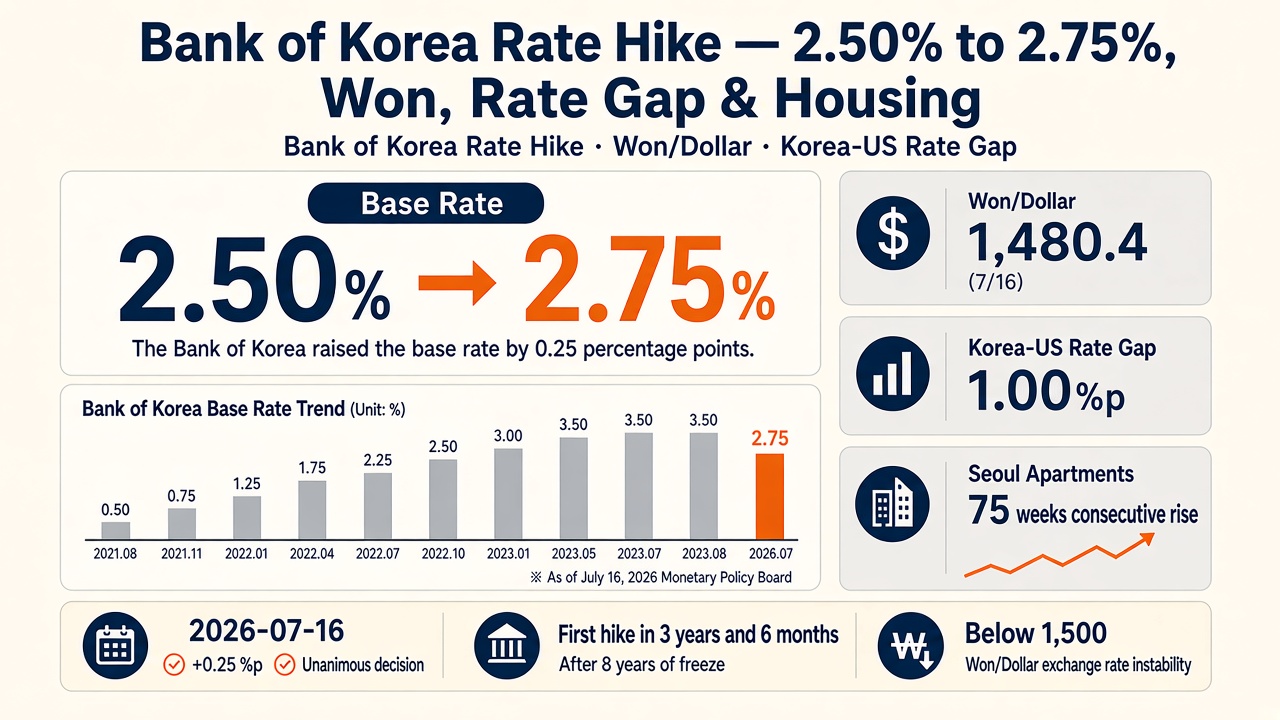
The Bank of Korea rate hike on July 16, 2026 raised the policy rate from 2.50% to 2.75% (+0.25%p). It was the first hike since January 2023—about three and a half years—and the seven Monetary Policy Board members voted unanimously.
The same day, the Seoul USD/KRW fixing at 3:30 p.m. was 1,480.4 (intraday in the 1,470s)—a different zone from early July near 1,560 and the 1,500s. The Korea–US rate gap versus the Fed’s upper bound (3.75%) narrowed from 1.25%p to 1.00%p.
This piece starts with what the policy rate is, then connects FX, mortgages, housing, household debt, and East Asia (China, Japan, energy) only where sourced numbers reach. Further hikes and house prices stay conditional. This is not advice to buy, sell, or convert any currency, bond, property, or stock.
What is the policy rate — and why it touches FX and mortgages
The Bank of Korea’s base rate is the policy interest rate that anchors how the central bank and commercial banks price short-term funds. When that anchor moves, deposit and lending rates customers see tend to follow with a lag.
Home mortgages are the channel households feel most. A large floating-rate share means policy moves can pass into monthly interest faster. Fixed-rate loans still reprice for new borrowers when market rates and bank spreads shift.
FX is messier. A narrower Korea–US gap can ease some “Korea looks worse on carry” pressure—but USD/KRW also moves with the dollar itself (DXY), foreign equity flows, and exporters selling dollars. Rates alone do not set the won.
-
1
① Policy rate
BOK policy rate (now 2.75%)
-
2
② Bank funding & loan rates
Passes to deposits/loans with a lag
-
3
③ Mortgage interest
Faster if floating-rate share is high
-
4
④ FX & flows
Gap, DXY, foreign flows move together
Bank of Korea rate hike — what July 16 decided
The BOK cited firmer growth (exports and investment), inflation likely above the 2% target for a while, and financial-stability risks (FX volatility, Seoul-area housing, household debt). The statement said the Board needs to continue a rate-hiking stance.
June 2026 CPI was +3.2% YoY (May +3.1%); core (ex food and energy) held at 2.5%. Growth this year may “substantially exceed” the May forecast of 2.6%, and June exports cleared $100 billion for the first month on record, per the governor’s opening remarks.
Markets had widely priced a July 25bp hike. So this was not an “expected hike vs surprise hold” gap—it was a priced hike that arrived. The open question is how fast to go at the Aug 27, Oct 22, and Nov 26 meetings.
Governor Shin said August remains “all options open” until inflation convincingly converges to target. The Bank also lifted its financial intermediary support facility rate from 1.00% to 1.25%. The official text is the BOK Monetary Policy Decision (July 16, 2026).
2024–2026 path — four cuts, eight holds, then a hike
To place the hike in the cycle, string the prior cuts and holds. From October 2024 through May 2025, four cuts took the rate from 3.50% to 2.50% (−1.00%p total).
- 2024-10-11: 3.50 → 3.25 (cut)
- 2024-11-28: 3.25 → 3.00 (cut)
- 2025-02-25: 3.00 → 2.75 (cut)
- 2025-05-29: 2.75 → 2.50 (cut)
- 2025-07 ~ 2026-05: held at 2.50 (eight holds, ~14 months)
- 2026-07-16: 2.50 → 2.75 (hike)
At the May meeting, 19 of 21 six-month-ahead dots sat above 2.50%—a signal consistent with July’s hike. The bar chart below is that path in numbers only.
BOK policy rate path 2024–2026 cuts holds hike bar. BOK decisions/press. Cuts from Oct 2024 → 2.50 May 2025 → eight holds → 2.75 on Jul 16, 2026. Not advice.
Won, Korea–US gap, DXY — numbers that overlapped this week
USD/KRW approached ~1,560 in early July, rose into the 1,500s mid-month (BOK wording), then eased toward the upper 1,400s as supply/demand improved. Around July 8, intraday prints near 1,498 broke below 1,500; the July 16 fixing was 1,480.4.
On July 17 (Constitution Day holiday session), the market printed about 1,478.50 near 3:30 p.m. Thin holiday volume warrants caution, but the latest zone is around 1,480—and below the 1,500s.
The Korea–US gap here is Fed target 3.50–3.75% (held June 17, 2026) using the 3.75% upper bound minus the BOK rate: 1.25%p at 2.50% → 1.00%p at 2.75%. Yonhap frames that as the smallest gap in about three years and four months since March 2023.
DXY scores how strong the dollar is versus a basket of majors. Roughly 100.493 on July 16 (−0.751) and 100.674 on July 17. That day, the BOK hike plus softer US PPI weakened Fed-hike bets—DXY soft and won-firming pressure showed up together. The link is regime-dependent; we do not claim one long-run correlation. For dollar/equity regimes, see also our US market correction & DXY history note.
Early–mid July
Won ~1,560 → 1,500s
·
· · Gap 1.25%p (BOK 2.50%)
· · Outflows / dollar strength cited
Jul 16–17 (post-hike)
Won ~1,480s (below 1,500)
·
· · Gap 1.00%p (BOK 2.75%)
· · DXY ~100.5 + won firming together
Mortgages, housing, household debt — the domestic channel
The BOK statement flagged Seoul-area house-price gains and faster household-debt growth as financial-stability risks. Household credit (provisional) hit a record 1,993.1 trillion won at end-Q1 2026 (+14 trillion QoQ). Housing-related loans were 1,178.6 trillion (+8.1 trillion).
Bank household loans rose +7.6 trillion in June 2026 (largest in about 22 months); mortgages alone +4.3 trillion (stock ~945 trillion). The governor cited financial-sector household loan growth near 8–9 trillion a month.
Mortgage rates were already climbing. Big-five banks’ new fixed mortgage quotes around July 9 ran about 4.65–7.37% (vs 4.26–7.10% end-May). After the hike, some banks raised floating spreads/ceilings (e.g. KB +0.15%p in press reports).
Korea Real Estate Board (week of July 13): Seoul apartment sales +0.30%, jeonse +0.28%—a 75th straight week up. Hwaseong Dongtan +0.73% that week. KB (week of July 6): Seoul sales +0.22% (second week of slower gains); Dongtan +1.36% (down from 2.27% prior).
On June 30 the government designated Dongtan, Giheung, and Guri as regulated/speculation zones (effective July 1), cut LTV for first-home buyers from 70% to 40%, and largely barred mortgages for owners already holding homes. Land-transaction permits from July 5 add owner-occupancy rules that curb gap investing. The governor said monetary policy alone cannot “fix” house prices—macroprudential tools complement. A hike can constrain demand via interest costs and expectations, but size and lag are not forecastable here.
Household credit bank loans mortgage growth bar. Jun bank HH +₩7.6tn · mortgages +₩4.3tn. Governor: financial-sector ~₩8–9tn/mo. Stock ₩1,993tn & LTV 70→40% in body. Not advice.
East Asia — only facts that touch the won or inflation
China’s Q2 2026 GDP grew +4.3% YoY (Q1 +5.0%), under the 4.5–5% annual target band. Weak domestic demand and property versus strong exports (June exports ~+27% YoY in reports) can affect Korea indirectly via global demand, commodities, and risk appetite. We do not claim China GDP caused the BOK decision.
Japan: the BOJ hiked on June 16, 2026 (press); USD/JPY around 162 near July 16–17; the finance minister warned of “appropriate steps” if needed. Yen moves can spill into KRW via KRW/JPY crosses and Asian FX co-movement.
US–China trade (e.g. the 10% universal tariff sunset around July 24) and Middle East energy appear in the BOK statement. Oil and inflation expectations can feed CPI → the BOK path. That overlaps our oil, Iran, Hormuz piece. Taiwan/North Korea lack direct FX-number quotes in that week’s official BOK/Seoul FX texts, so we do not stretch them here.
What to watch next — August and October as if/then only
If July was priced, the next variable is hike pace. Below is if/then framing—not targets or trade signals. For a Fed wallet frame, see our Fed hold / wallet impact note.
- If CPI stays sticky in the 3%s and household loans keep running hot → the “continue hiking” line and open August option read heavier.
- If growth/exports soften more than expected or markets get volatile → the Board may slow timing/pace (the statement already ties decisions to data checks).
- If DXY strengthens again and foreign equity outflows rise → a narrower rate gap alone may not stabilize the won.
-
1
① Watch list
CPI · HH loans · growth/exports · DXY
-
2
② Sticky CPI & credit
Hiking stance / Aug option reads heavier
-
3
③ Growth/vol worsen
Room to slow timing/pace
-
4
④ Dollar/outflows return
Gap alone ≠ won stability
In one line: the meeting’s point is not “did they hike?”—it is that policy is back at 2.75% with a stated hiking stance. FX sits near 1,480 / below 1,500; the gap is 1.00%p; housing and debt move with rates and regulation together. Numbers will keep updating.
Educational/informational only. No recommendations on FX timing, mortgage refinancing, apartment trades, or bond/equity weights.
The hike is one node — won, the US–Korea gap, mortgages and housing each need their own numbers.
Sources
- BOK — Monetary Policy Decision & Opening Remarks (July 16, 2026)
- Yonhap — Full text of BOK July monetary policy statement
- 연합뉴스 — 한은 기준금리 0.25%p 인상(종합)
- 연합뉴스 — 환율 두 달 만에 최저(1,480.4원)
- 연합인포맥스 — 2026-07-17 달러-원 마감
- 조선비즈 — 7월 통화정책방향 의결문
- 연합뉴스 — 가계신용 1,993조
- 연합뉴스 — 6월 은행 가계대출 7.6조↑
- 조선일보 — 한국부동산원 7월 2주
- 뉴시스 — 동탄·기흥·구리 규제
- BBC — China Q2 GDP 4.3%
- FXStreet — Yen intervention warning / USDJPY
- Federal Reserve — FOMC June 17, 2026
- 국가데이터처 — CPI
For information only — this is not a recommendation to buy or sell any asset.
Comments 0