IMF Hedge Fund Warning: Treasury Share Up From 4% to 9% — How Margin Calls Could Reach Korean Firms
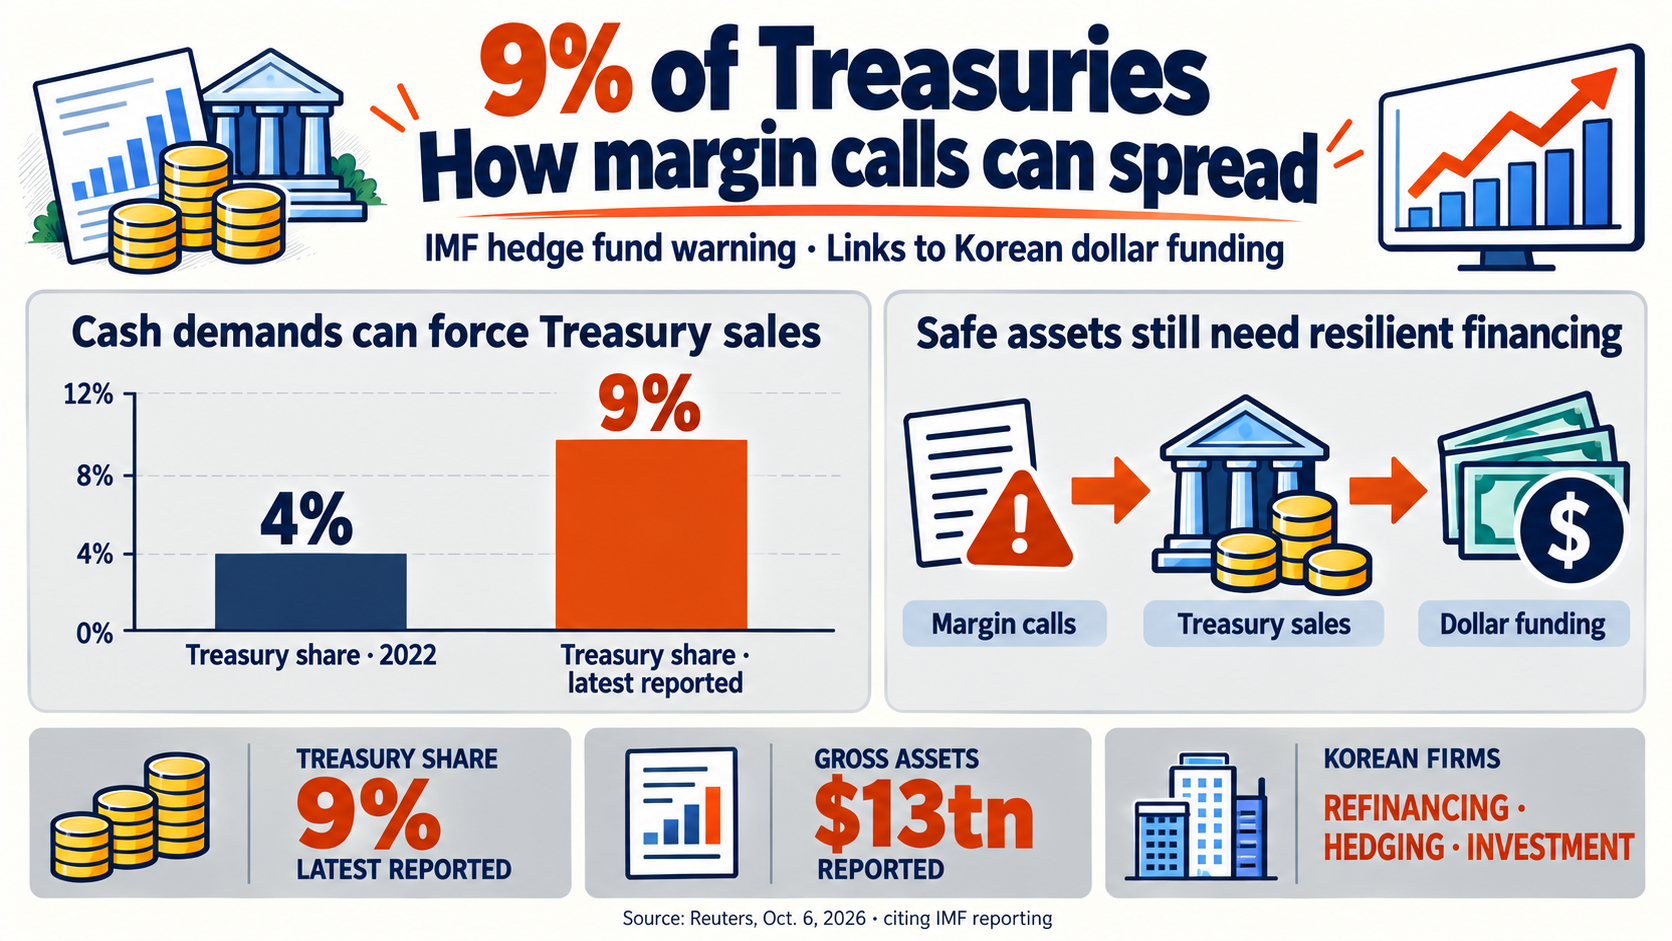
The IMF hedge fund warning concerns the financing behind apparently safe assets. Reuters reported on October 6 that hedge funds’ share of the Treasury market has risen from 4% in 2022 to 9%. Understanding the borrowing behind those holdings helps explain how market stress could reach Korean companies. Source: Reuters · 2026-10-06
For a corporate treasurer, the immediate question is practical: can the company refinance its dollar debt next month, and might its currency contracts require more cash collateral? Those links connect a fund’s trading book to a manufacturer’s investment budget.
This article is dated October 7, Korea time. The IMF page confirms the Chapter 2 release schedule; current headline figures come from reporting on that chapter. Its underlying tables were not directly available for verification. Federal Reserve research supports the trading mechanics. The Korean business implications below are conditional analysis, not reported company losses. Source: IMF · October 2026 GFSR Source: Federal Reserve · 2026-06-22
The IMF hedge fund warning: assets versus exposure
Hedge funds pool capital from sophisticated investors and use varied strategies across securities and derivatives. The word “hedge” does not guarantee protection. Funds may offset one position with another or borrow to expand a trade. They sit outside banking but rely on banks for financing and derivatives services. Source: New York Fed · 2025-10-16
Reported gross assets are about $13 trillion; derivatives-inclusive notional exposure is reported above $40 trillion. Notional amounts describe contract scale, not cash invested or losses. Source: Reuters · 2026-10-06 Source: Cinco Días · 2026-10-06 Source: Ahram Online · 2026-10-06
Gross assets: about $13tn
Includes assets financed with borrowing
Meaning
Caution · Not investor equity
Notional exposure reported above $40tn
Includes derivatives contract amounts
Meaning
Caution · Not expected losses
Offsetting contracts can make gross exposure large while reducing sensitivity to price direction. Cash needs are a different matter. Gains and losses may settle with different counterparties at different times, leaving a fund short of immediately usable money even when the eventual net result is modest.
Dividing 40 by 13 does not produce an equity leverage ratio. That assessment requires net assets, borrowing, offsetting positions and collateral terms. These large totals justify scrutiny; they do not measure an impending default bill.
Why buy Treasuries and sell futures?
A common strategy is the cash-futures basis trade: buy a Treasury and sell a futures contract against it. The objective is to capture a price discrepancy as it converges, after financing and other costs. It is different from a simple bet on whether interest rates rise or fall. Source: Federal Reserve · 2026-06-22
Repo financing supplies cash against the Treasury collateral, usually for a short term. Modest collateral requirements let funds control large positions with relatively little capital. A small pricing gap can then offer an attractive return on that capital. This helps explain the expansion of arbitrage activity. Source: Federal Reserve · 2023-09-08
More participation can narrow pricing discrepancies and improve trading conditions. The reported rise in market share also reflects a larger intermediation role. It does not mean every fund follows the same strategy. Source: Reuters · 2026-10-06
A larger Treasury-market footprint. Reuters, October 6, 2026. Precise observation date and denominator require the IMF tables. Not a share of turnover or directional bets.
A June 22, 2026 Federal Reserve note estimates that large hedge funds held about 8.5% of privately held Treasuries by market value in September 2025. That supports the broad direction of expansion, but differences in sample, denominator and timing prevent treating it as an identical series to the IMF figure. Source: Federal Reserve · 2026-06-22
Financing costs can erase the appeal of the trade. The IMF’s April stability report describes how higher repo rates and binding risk limits can push funds to unwind positions. When the underlying profit margin is narrow, a relatively small funding change can matter. Source: IMF · April 2026 GFSR Chapter 1
When a margin call arrives, timing matters
A margin call requires additional cash or collateral. Daily settlement of a futures loss is different from an increase in the buffer required against future losses. Repo lenders can also reduce the amount they advance against collateral or decline to renew financing. Each creates a different liquidity demand. Source: Federal Reserve · 2023-09-08
Suppose Treasury prices rise. A fund can gain on the bond while owing cash on its short futures position. The bond’s unrealized gain does not automatically move into the futures account. If bond prices fall, collateral value may shrink while the short futures position gains. The distinction prevents confusing a liquidity shortfall with a net investment loss.
A fund unable to raise cash reduces positions, selling the bond and buying back the futures. If many funds do this together, dealers may lack capacity to absorb the trades. Larger pricing dislocations can then generate further collateral pressure. Source: Federal Reserve · 2026-06-22
-
1
Funding terms change
Repo renewal or margin requirements
-
2
Immediate cash need
Unrealized gains are not cash
-
3
Positions shrink
Sell cash bonds; buy back futures
-
4
Dislocations can widen
Crowded exits can reinforce stress
Prime brokers supply financing, securities lending and derivatives services. A bank focused only on its own relationship may miss a fund’s borrowing elsewhere. Having collateral is different from knowing the price at which it could be sold when many clients exit together. Source: New York Fed · 2025-10-16
Forced sales pressure the affected bonds, but safe-haven demand during a growth scare can pull yields lower. The final direction depends on the shock and policy response. The more robust concern is the potential for abrupt price moves and expensive execution.
How the pressure could reach Korean companies
A Korean issuer’s dollar borrowing cost combines a benchmark market rate with compensation for credit risk and market conditions. Even if Treasury yields stabilize, less willing lenders can demand a larger spread. Firms approaching a refinancing date would feel this channel first.
Banks obtain dollars and lend them to businesses. Tighter counterparty limits or collateral requirements can change the price and tenor of that lending. Companies with long-dated fixed-rate funding are differently exposed from those repeatedly rolling over short-term loans. This is a possible transmission mechanism, not evidence that such a tightening has already occurred.
Currency hedges lock in exchange terms for future dollar receipts or payments. They reduce exchange-rate uncertainty but do not eliminate funding needs. Tight dollar supply in swap markets can change pricing, and collateralized contracts may require cash before maturity. Interest differentials, tenor and the direction of the hedge also matter. Source: IMF · April 2026 GFSR Chapter 2
Potentially greater pressure
Frequent short-term refinancing
Debt
Dollar flows · Payments precede receipts
Collateral · Little cash for extra calls
Factors that can cushion stress
Long maturities and fixed funding
Debt
Dollar flows · Matched payment and receipt dates
Collateral · Available cash and diversified counterparties
The following business implications are analysis. A weaker won can lift translated export revenues, but imported inputs and dollar interest payments may cost more. Net dollar cash flows and payment dates matter more than the exporter label alone. The exchange-rate direction itself remains uncertain.
Persistently higher funding costs raise the return required to justify factories, data centers or power projects. Strong technology or orders may not be enough to secure financing. Our earlier discussion of World Bank private capital mobilization similarly distinguished support commitments from financial close.
Cash-rich businesses with secure financing may keep investing while refinancing-dependent competitors delay expansion. If persistent, that divergence can alter market shares and supplier orders. Households may face higher debt-service costs or weaker asset values, weighing on consumption. A brief market disruption, however, need not become a recession.
Reserve valuation losses are different from a shortage of usable dollars. In stress, the liquidity of assets available for sale or collateral matters. This article does not assess Korea’s reserve adequacy or conclude that intervention is necessary. Source: IMF · April 2026 GFSR Chapter 2
What the IMF, the Fed and Seoul are saying: the shock versus its amplification
At the IMF’s October 1 briefing, communications director Julie Kozack discussed energy prices, policy expectations, debt concerns and term premiums as drivers of higher yields. A term premium compensates investors for uncertainty over a longer holding period. She also described bond markets as orderly. Vulnerability is not the same as an ongoing market breakdown. Source: IMF · 2026-10-01
In a May 8 speech, Fed supervision vice chair Michelle Bowman argued that broad reporting categories obscure banks’ exposures to nonbanks, and described plans for more detailed borrower information. Her remarks focused on private credit and predate this IMF chapter. The relevant connection is the need to understand links across the banking boundary. Source: Federal Reserve · 2026-05-08
The IMF recommendations reported by Reuters emphasize closing data gaps and improving monitoring. In practical risk management, aggregate borrowing must be considered alongside prime-broker limits, collateral and correlated exits. That is a supervisory task distinct from setting policy interest rates. Source: Reuters · 2026-10-06
Korea’s finance ministry announced on October 1 that October Treasury issuance would be reduced by KRW 5 trillion from the original plan. Less new supply can ease local absorption needs. It does not directly repair offshore dollar limits or US repo markets, and the evidence reviewed does not establish hedge-fund liquidation as the cause of the Korean decision. Source: 재정경제부 / KDI · 2026-10-01
Our earlier article on Treasury yields and Korean corporate costs examined the transmission of higher rates. This IMF hedge fund warning adds a question about who might be forced to trade. Distinguishing the original shock from amplification helps clarify the policy response.
Equity sentiment has improved, but it does not measure funding resilience. The supplied CNN snapshot reads 48.0, neutral, on October 6: up 19.2 points from a week earlier and 2.8 from a month earlier. GoldKimp’s KOSPI reading is 60.5, greed, dated October 1. Korea’s classification is more optimistic, but differing methods and dates prevent direct numerical comparison. Korean weekly and monthly changes are unavailable. Source: CNN Fear & Greed Source: GoldKimp KOSPI F&G
Current Smart Money and Dumb Money values and dates were blank on SentimenTrader’s public dashboard. Its September 25 summary says their spread crossed above zero on September 16. That is a dated observation, not a current reading. Better equity sentiment is not proof that collateral and short-term funding will remain available. Source: SentimenTrader Source: SentimenTrader · 2026-09-25
Watch repo, collateral and dollar-funding terms, not just one yield
Watch whether markets remain usable: repo rates and collateral demands, Treasury bid-ask conditions, bank dollar-funding spreads and currency-hedging quotes. These are ways to test whether the vulnerability is spreading, not a forecast that each measure must deteriorate.
If collateral terms and refinancing remain stable, funds can continue to help align prices. If many must cut borrowing at once, a trading dislocation can travel into investment plans. For Korean businesses and investors, asset quality should be assessed alongside the timetable of cash needed to hold those assets.
Sources and references
- IMF — October 2026 GFSR 발표 일정
- Reuters / MarketScreener — Hedge funds market footprint, 2026-10-06
- Cinco Días — IMF 헤지펀드 보고서 보도, 2026-10-06
- IMF — Julie Kozack 브리핑, 2026-10-01
- Federal Reserve — Michelle Bowman 연설, 2026-05-08
- Federal Reserve — Treasury Exposures, Repo, and Margining, 2023-09-08
- New York Fed — The Basics of Hedge Funds, 2025-10-16
- IMF — April 2026 GFSR Chapter 1
- IMF — April 2026 GFSR Chapter 2: Capital Flows
- 재정경제부 / KDI — 2026년 10월 국고채 발행계획, 2026-10-01
- CNN — Fear & Greed, 2026-10-06 스냅샷
- GoldKimp — KOSPI F&G, 2026-10-01 스냅샷
- SentimenTrader — 공개 대시보드
- SentimenTrader — 2026-09-25 공개 주간 요약
- SentimenTrader — 2026-10-02 공개 주간 요약
- Federal Reserve — Decomposing Hedge Funds’ U.S. Treasury Exposures, 2026-06-22
- Ahram Online — IMF 명목노출 40조달러 초과 보도, 2026-10-06
For information only — this is not a recommendation to buy or sell any asset.
Comments 0