India GST tax cuts — revenue rises 14.8%, but who benefits?
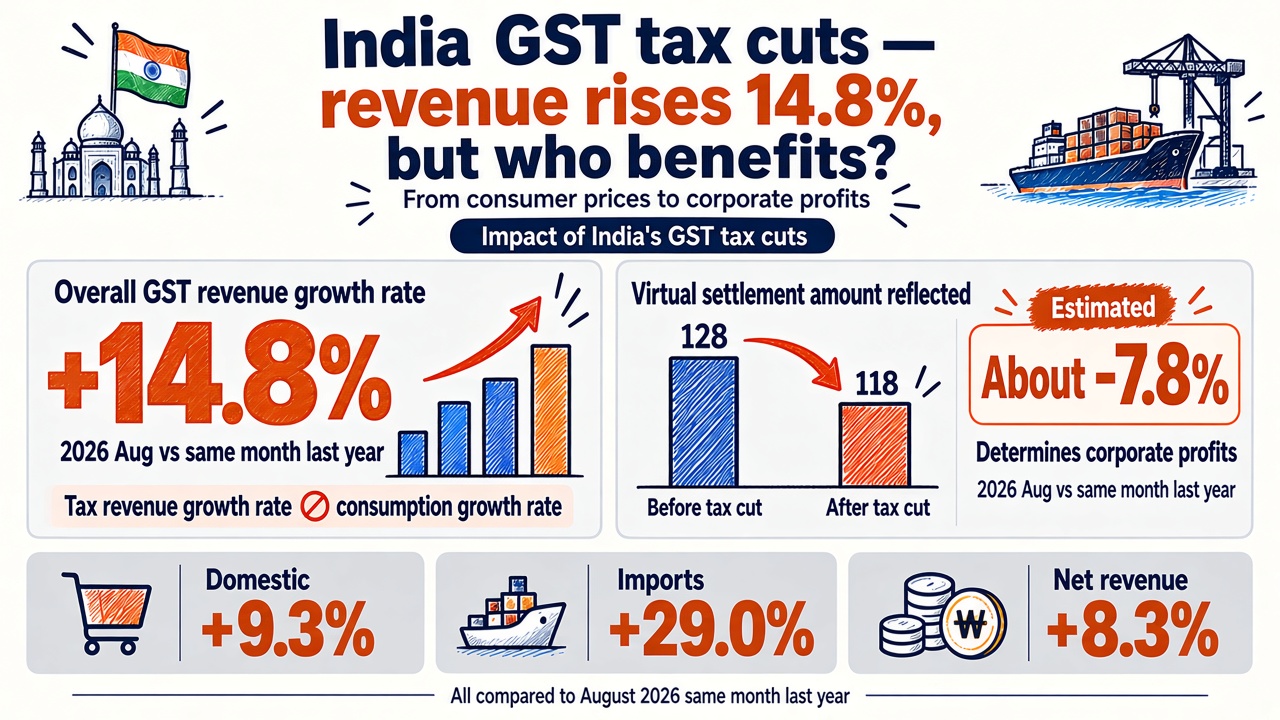
India GST tax cuts are approaching their first anniversary. August 2026 gross collections rose 14.8% from a year earlier, but that is not a measure of consumption growth. The useful question for Korean businesses is how lower taxes reach the checkout price, factory output and, eventually, profit. PTI, September 1.
India lowered taxes on many consumer goods from September 22, 2025. With a year nearly elapsed, the opening discount matters less than whether customers keep buying. An extra car sold in India can mean very different things for its manufacturer, an Indian component supplier and a Korean exporter.
The information cutoff is September 15, 2026. Policy details and reported figures are sourced below. The implications for earnings and economic activity are conditional analysis.
India GST tax cuts: start with the checkout price
GST is an indirect tax on goods and services. The amount a customer pays includes money the seller must remit as tax; it is not all company revenue. Eligible businesses can offset tax already paid on inputs. A lower checkout price therefore need not reduce the manufacturer’s revenue per unit if the price before tax stays unchanged.
The finance ministry’s reform announcement lowered GST from 28% to 18% for air conditioners, certain televisions and small cars, among other products. Rates remain product-specific. Vehicle dimensions, engine size and the old compensation cess also matter when calculating the actual change. Finance ministry reform announcement.
Take an illustrative product priced at 100 before tax, with no other taxes. A 28% GST produces a bill of 128. At 18%, full pass-through brings it to 118. The tax rate falls by 10 percentage points, while the customer’s bill falls about 7.8%. This is arithmetic, not an observed vehicle discount.
Before
100
Pre-tax price
GST · 28
Total bill · 128
After
100
Pre-tax price
GST · 18
Total bill · 118
For a large purchase, that saving can change the decision. A smaller loan principal also means smaller instalments, with other terms unchanged. Yet a household without access to credit, or uncertain about its income, may still postpone the purchase.
Why 14.8% higher tax receipts do not establish a consumer boom
The August breakdown makes the distinction clear: gross receipts rose 14.8%, domestic receipts 9.3% and import-related receipts 29.0%. After refunds, overall net revenue grew 8.3%. These figures were checked against the reproduced government table and reporting by PTI and Business Standard. Revenue table; Net-revenue report.
India: August 2026 GST revenue growth. Provisional GSTN table reproduced by Taxguru; checked against PTI and Business Standard. Gross, domestic and imports are before refunds; net is after refunds. Bars are not additive.
Tax receipts depend on prices, effective tax rates, the mix of goods and the timing of reporting and payment, as well as transaction volumes. Faster import-tax growth does not mean households bought proportionately more. Machinery and intermediate goods can also be part of the import bill.
Refunds have a separate cash-flow effect. Faster repayments can restrain growth in the government’s net receipts while returning cash to businesses sooner. That may ease the financing of inventories and inputs. A single tax-growth headline misses this distinction.
Nor does rising revenue prove the tax cut paid for itself. That would require estimating receipts in a world without the reform. The release describes nominal collections; it does not isolate the reform’s contribution to economic growth.
The benefit reaches households through actual prices
Pass-through means the share of a tax saving that reaches the customer. Lowering the final bill passes the benefit on. Keeping the bill unchanged while raising the pre-tax price leaves some with the seller. Higher materials or transport costs may absorb that money. The checkout bill is what matters to households.
A March 2026 NIPFP working paper compared consumer-price indices over four months before and four months after the reform. Some durables became cheaper, while results for food and household goods were uneven. It is a descriptive comparison, not a causal estimate, and does not cover August prices. NIPFP Working Paper 444.
The commercial question is how competition works. When customers can compare brands and wait, sellers have a stronger reason to pass savings through. Supply shortages or limited alternatives can let suppliers retain more. Determining which mechanism dominated requires product-level prices and costs, rather than assumptions about an entire sector.
For Korean companies, watch utilisation and discounts after volume
Hyundai Motor India reported August 2026 domestic sales of 54,396 vehicles, up 23.6% year on year. Higher local sales are a reported result. Company sales, however, are distinct from final customer registrations and do not represent consumption across India. Hyundai Motor India release.
But how much did the company keep? The sales figure alone cannot establish either the contribution of the tax cut or the increase in profit.
The route to higher profit is straightforward. More units from the same factory spread relatively fixed expenses, such as depreciation, over a larger output. Suppliers can benefit from additional orders and better use of their existing equipment. This is why capacity utilisation matters alongside sales volume.
-
1
Lower tax
Passed to the final bill
-
2
More purchases
Lower financing need
-
3
Higher output
More use of existing capacity
-
4
Potential profit gain
Discounts and costs still matter
Company-funded discounts change the calculation. Unlike a tax reduction, a discount cuts the money the business receives. A shift toward cheaper models or the start-up expenses of a new factory can also limit profit growth. Quarterly volume, average selling price and operating margin should therefore be read together.
Appliance makers with local factories and distribution can also respond to demand. LG announced the start of construction of its third Indian plant in May 2025. That predates the GST reform, so the tax cut cannot explain that initial investment decision. The relevant question is how much future demand fills the capacity already being added. LG construction announcement.
Local production and Korean exports can move differently
A product made and sold in India is different from a finished product shipped from Korea. Local sales may support the parent’s consolidated earnings without increasing output at Korean factories. The domestic spillover depends on the balance between Korean equipment and components and locally sourced inputs.
Sustained demand can make local sourcing more attractive by shortening delivery times and reducing inventories. Indian suppliers and employment could gain while Korean exports of the same components grow less than expected. Equipment makers and suppliers of components that are difficult to source locally could still receive additional orders.
This connects with the distinction discussed in China’s export expansion and Korean industry. A growing foreign market and a larger share of that market for Korean suppliers are separate propositions.
Three checks for equities and the next quarter
A tax cut can bring purchases forward. If a household buys this year instead of next, current sales rise partly at the expense of future demand. Continued purchases beyond the initial response, without excessive dealer inventories, would provide better evidence of a lasting improvement.
If households spend their savings elsewhere, the benefit can extend to restaurants and services. Debt repayment or purchases of imported goods would produce a different domestic response. This transmission is central to the support for domestic demand described in Reuters’ August 2025 reporting on the reform proposal amid trade tensions. Reuters policy background.
For equities, the price paid for expected earnings is another variable. Strong results can produce a muted response if investors already expected more. Indian business exposure, ownership in the local subsidiary and currency translation also affect what reaches the Korean shareholder. No specific post-reform share-price reaction is asserted here.
The next checks are final customer sales alongside dealer inventories; profitability per unit after discounts alongside factory utilisation; and tax collections after distinguishing refunds alongside company cash flow. Agreement across those measures would strengthen the case for an earnings improvement rather than a temporary sales bounce.
The time it takes for corporate gains to reach households and investment also matters in the link between Korean profits and household income. India GST tax cuts will ultimately be judged through actual prices, sustainable sales and the orders that support investment and employment.
This is economic analysis, not a recommendation to buy or sell a security.
A tax cut delivers when customers pay less and businesses sell more without sacrificing their margins.
Sources
- GSTN 2026년 8월 세수표 재수록 — Taxguru, 2026-09-02
- PTI — 2026년 8월 GST 세수, 2026-09-01
- 인도 재무부 — 제56차 GST 위원회 권고, 2025-09-03
- NIPFP Working Paper 444 — GST 2.0과 소비자가격, 2026-03-17
- 현대차 인도 — 2026년 8월 판매 실적, 2026-09-01
- LG전자 — 인도 스리시티 제3공장 착공, 2025-05-08
- Reuters — 인도 소비세 개편 추진 배경, 2025-08-15
- Business Standard — 8월 순 GST 세수 8.3% 증가, 2026-09-01
For information only — this is not a recommendation to buy or sell any asset.
Comments 0