Japan tourism arrivals fell 9.6% — Why hotel and airline earnings may differ
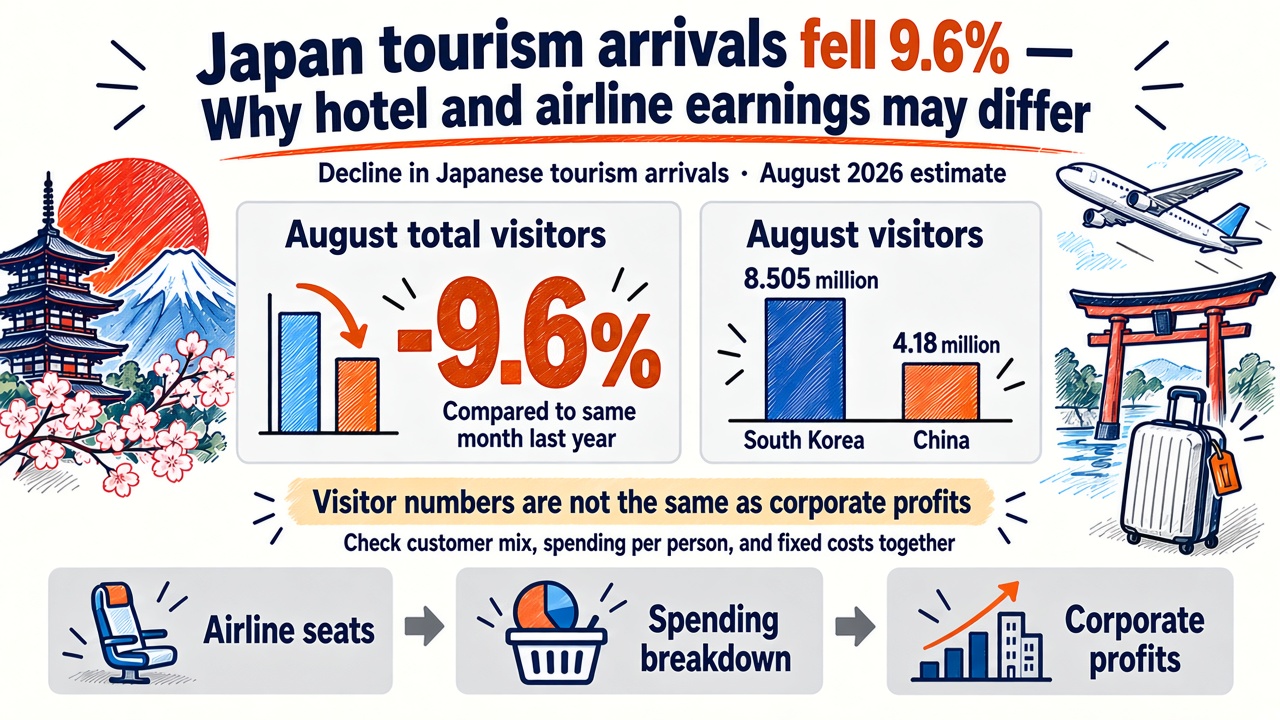
Foreign arrivals in Japan fell 9.6% in August 2026 to 3,098,900. But the decline in Japan tourism arrivals can affect hotels, duty-free retailers and Korean airlines differently. Who visits, where they spend and how much revenue remains after costs determine the impact on each business. JNTO, September 16
Arrivals from Korea increased even as the total fell. A particular route or destination can therefore grow within a shrinking aggregate market. The latest release is a story about the composition of demand as well as its size.
Information is current to September 17, 2026. August arrivals and second-quarter spending are identified separately below. Earnings and investment implications are conditional analysis, not reported company results or investment recommendations.
Japan tourism: not every market declined
JNTO reports that 14 source markets set August arrival records. Weakness in the total coexists with growth elsewhere, making a worldwide loss of interest in Japan an incomplete explanation. Reuters reporting in Japanese corroborates the headline decline.
Korean arrivals rose 28.7% to 850,500, while Chinese arrivals fell 59.0% to 418,000, according to Travel Voice’s reporting of JNTO figures. Kyodo corroborates the Korean figure; FNN separately reports a roughly 60% Chinese decline.
August 2026 arrivals: Korea 850500 and China 418000. August 2026 estimates. Korea +28.7% YoY; China -59.0%. Source: Travel Voice citing JNTO; cross-checked against Kyodo and FNN. Counts, not spending.
The chart compares only these two source markets, not the total or their spending. More Korean arrivals do not establish that Korean visitors spent more than Chinese visitors. Length of stay, accommodation and shopping all affect the bill.
JNTO arrivals also extend beyond leisure tourists and include certain expatriate and student entries. An arrival is neither a hotel booking nor an overnight stay. Treating these measures as interchangeable can distort business estimates.
An attractive exchange rate cannot create airline seats
JNTO mentions reduced flight services and typhoon cancellations in some markets. Fewer departures can prevent people from travelling on preferred dates. Higher fares or longer connections may also lead potential customers to postpone a trip.
The economic cost of travel includes tickets, accommodation, time and cancellation risk. A favourable yen exchange rate can be offset by expensive flights. Currency movements alone therefore cannot explain the change in arrivals.
Causation can run both ways. Airlines may cut flights after bookings weaken; fewer flights may then further constrain bookings. Observing a capacity reduction does not establish that weaker household demand was the original cause.
Weather disruption and sustained route reductions also have different recovery paths. Cancelled services may resume after a storm, while rebuilding scheduled capacity takes planning and sufficient demand. The release does not quantify each factor’s contribution. Ordinary seasonal slowing is not, by itself, an explanation for a year-on-year August decline.
Second-quarter spending held up despite fewer visitors
The Japan Tourism Agency’s first preliminary estimate puts April–June inbound spending at ¥2.5096 trillion, up 0.2% year on year. Spending per visitor rose 3.3% to ¥244,000. These are nominal yen amounts, as reported in the official spending release.
At its July briefing, the agency said higher spending per visitor supported total expenditure despite fewer visitors. It also said the reasons behind the United States becoming the largest source market by total spending needed further analysis. An observed ranking is not sufficient evidence of a particular currency effect. Official briefing
Within a consistent survey population, total spending can be understood as visitor numbers multiplied by spending per visitor. The latter depends on duration, daily expenses and shopping. Fewer people staying longer can sustain total expenditure. Higher prices can also lift nominal spending without increasing the quantity of services consumed.
Multiplying August arrivals by the second-quarter spending average would mix seasons, visitor groups and statistical coverage. The earlier quarter demonstrates that falling numbers can coexist with rising expenditure. It does not establish that August spending increased.
A separate arithmetic illustration helps show the scale involved. In an otherwise identical population, a 9.6% decline in visitors requires about 10.6% more spending per visitor to keep the total unchanged: 1 divided by 0.904, minus 1. This is neither an August spending estimate nor a forecast.
An empty hotel room and an empty shopping basket differ
For hotels, consider occupancy and the average rate charged for sold rooms together. Occupancy is the share of available rooms that are sold. Revenue per available room, or RevPAR, multiplies occupancy by that average rate. Stable prices can soften the revenue impact of lower occupancy; discounting alongside empty rooms compounds it.
Profit comes next. Rent and basic staffing costs do not immediately disappear when a few rooms are empty. These fixed costs can make profit fall faster than revenue. Conversely, filling more rooms with existing staff and facilities can allow a substantial share of additional revenue to reach profit.
-
1
Arrivals
Source market, destination and purpose
-
2
Room revenue
Room nights, occupancy and rates
-
3
Costs that remain
Rent, basic staffing and maintenance
-
4
Profit and investment
Cash generation affects expansion and renovation
Duty-free stores and department stores need a different set of measures: the share of visitors buying something, the value of each purchase and product margins. Extra hotel and restaurant spending does not automatically reach luxury counters. Nationality can provide context, but purpose of travel and actual expenditure categories are more informative.
Domestic customers also matter. The agency’s first preliminary estimate puts Japanese residents’ domestic travel spending at ¥7.5361 trillion in the second quarter, up 11.7%. This provides another source of demand, but does not show that domestic visitors filled any particular August vacancy. Domestic travel spending release
If differences in demand persist, investment may diverge too. A property dependent on group arrivals might delay expansion; a hotel in a resilient location might renovate existing rooms to support higher rates. These are possible management responses, not announcements by named companies.
An opportunity for Korean airlines, competition for domestic tourism
Growing Korean arrivals support the potential customer base for Korea–Japan airlines and travel agencies. Translating that into earnings requires more information: seats sold relative to capacity, realised fares and the cost of transporting each passenger.
Simultaneous route expansion can intensify price competition. Full aircraft do not ensure strong earnings if fares fall and fuel expenses rise. Companies with dollar-denominated costs must also watch the won. Our analysis of oil costs in Korea explains that expense channel.
Korean hotels and restaurants face a different possibility. A limited holiday budget spent in Japan may compete with domestic purchases. But the entire increase in outbound travel cannot be treated as lost Korean spending: some travellers would have visited another foreign destination, while others may have increased their overall holiday budget.
A decline in Chinese visits to Japan likewise does not prove a windfall for Korean duty-free stores. Travellers must actually choose Korea and make purchases for that mechanism to operate. They might instead travel domestically in China, visit another country or cancel a trip.
Inbound spending has the character of service exports for Japan. Lower purchases can reach local suppliers and employment, but one tourism release cannot establish an economy-wide recession. The distinction between company receipts and income reaching households is explored in our article on profits and household income.
The next figures to watch before judging tourism stocks
Equities may respond to revisions in future earnings rather than the arrival number alone. No broad share-price fall is asserted here; that requires separate market evidence. Hotel property values also depend on maintenance expenditure and financing costs alongside customer demand.
Watch whether airline capacity and bookings recover, then compare regional overnight stays and room rates. For retailers, examine duty-free revenue and purchase values. Third-quarter spending data will eventually cover a period that includes the August decline.
Returning bookings and stable room rates after services resume would be consistent with a temporary disruption. Prolonged weakness combined with discounting would put more pressure on fixed-cost-heavy operators, employment and expansion plans. Neither path is established by the current release.
Japan tourism needs to be read through the customers who arrive, where they spend and how much revenue remains after costs. That is how to distinguish a company that copes with fewer visitors from one that attracts more customers but earns little extra profit.
After counting visitors, follow their spending and the profit businesses retain.
Sources
For information only — this is not a recommendation to buy or sell any asset.
Comments 0