Semiconductor 3x Leverage Liquidation — SOXX −25%, SOXL −63%, Then Rebound
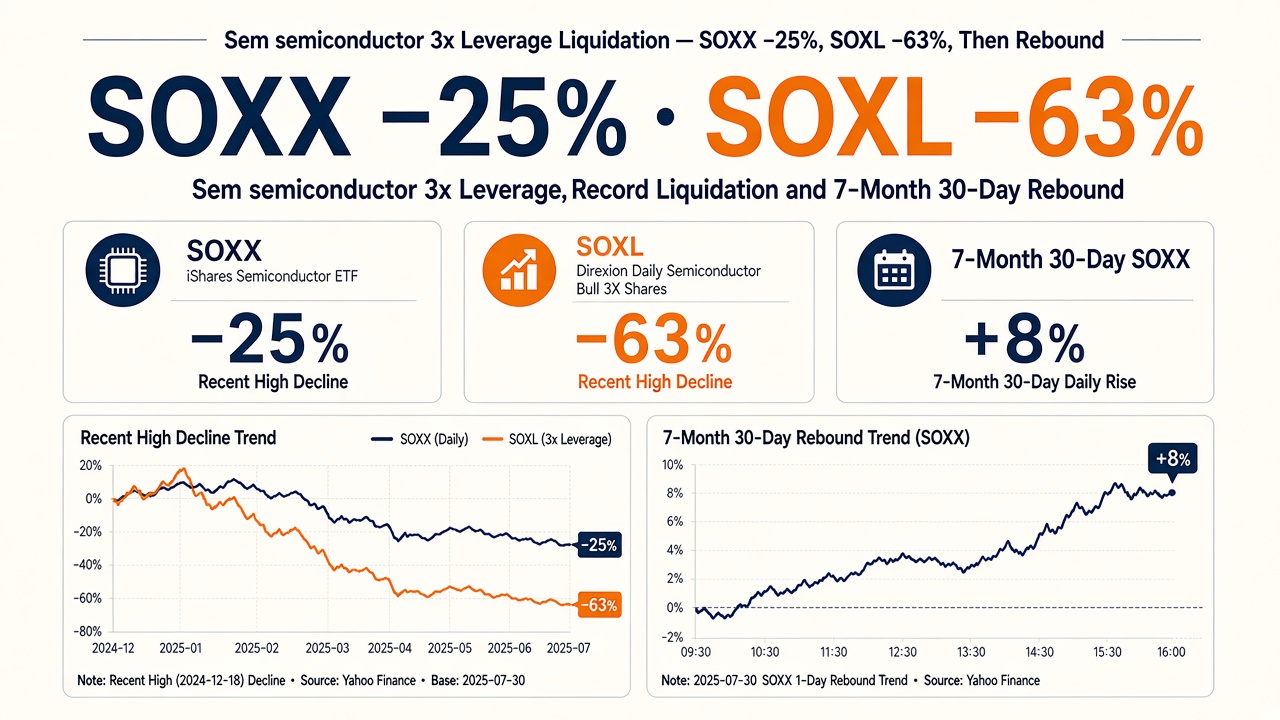
If you held 3x semiconductor leverage, the past few weeks felt endless. The unlevered iShares Semiconductor ETF (SOXX) fell roughly 25% from its June 22 peak, while Direxion’s daily 3x bull fund (SOXL) dropped about 63% over the same stretch. A 20–30% sector drawdown is the index story; leverage made the personal story much worse.
Then Thursday, July 30, 2026 flipped the tape. SOXX jumped about 8%. Micron, AMD, and SK Hynix ADRs posted double-digit gains. The Nasdaq rose 2.8% and ended a six-day losing streak. The spark was Microsoft’s Azure print.
So the question lands: Was this engineered to liquidate 3x positions? There is no public evidence of a single plot aimed only at retail SOXL holders. What did happen—and amplify both the slide and the bounce—are margin calls, forced selling, and daily leveraged-ETF rebalancing. This piece walks through that market plumbing. It is not a buy or sell recommendation.
At a glance — drawdown vs Thursday’s rebound
Put the numbers side by side. The same semiconductor narrative feels completely different in an unlevered ETF versus a 3x daily product.
- From the peak (approx.): SOXX −25% / SOXL −63% (from around the June 22 high)
- Gain needed to recover (approx.): SOXX +33% / SOXL +170% — choppy paths hurt SOXL more
- July 30: SOXX ~+8–8.5%; MU +15–18%; AMD +12–13%; SK Hynix ADR +15–17%; NVDA ~+2–3%
- Catalyst: MSFT ~+16% (Azure +43%, FY Azure $100B+). Meta −8–9% on FCF −91%
Bar chart of SOXX vs SOXL peak-to-trough decline. Approx. peak-to-trough from ~Jun 22. Compiled from multiple reports. Not advice.
What a 3x leveraged ETF actually is
A leveraged ETF trades like a stock but is built to deliver a daily multiple of an index’s return—three times, in SOXL’s case, versus a New York semiconductor benchmark. It is not a promise that semiconductors will return 3x over months.
Because cash equities alone rarely deliver that multiple cleanly, the manager uses swaps and futures. Reports put SOXL’s derivatives notional near half of net assets. Counterparties charge a spread over short-term rates (SOFR). That financing cost rarely appears as a neat fee line; it bleeds into daily performance.
A ~0.7% expense ratio therefore understates the economic cost of holding for weeks. Direxion’s own language is blunt: do not expect three times the cumulative index return for periods longer than a day.
Daily reset — why −25% became −63%
The fund resets every night. If the index falls 10% in a session, a 3x product targets about −30%. Shrink the asset base, and keeping 3x leverage means selling derivatives into weakness. A +10% bounce the next day only applies 3x to the smaller base. The index can be flat over two days while the leveraged share still sits lower.
Toy math: start at 100; −10% → 90; +11.11% → 100 again. The 3x path goes 70, then 70×1.333≈93.3. The index healed; leverage did not. That is volatility decay—or path dependence.
In a five-week, high-volatility slide, you can get something like the reported ~63% loss instead of a clean 3×25%=75%. In a smooth one-way rally, compounding can work in your favor. The product is not broken; it is a one-day tool held for many days.
-
1
Index falls that day
-
2
3x ETF loses a larger %
-
3
Smaller NAV → cut exposure (sell)
-
4
Next-day bounce is 3x on a smaller base
-
5
Index recovers; leverage still has a hole
Are forced liquidations and margin calls real?
Yes. They are just not the same story as ‘a cabal hunted retail SOXL.’ Different leverage layers stacked on the same tape.
A margin call is a broker or prime asking for more collateral when prices fall. Fail to meet it and you get forced liquidation—positions sold whether you like it or not. Hedge funds and retail credit accounts follow the same logic: contractual risk limits, often automated.
Late-July reporting described Goldman Sachs and JPMorgan pressing AI- and memory-heavy hedge funds for more collateral. Goldman commentary put roughly 16% of prime exposure in AI memory-related names as of June 30. Leopold Aschenbrenner’s Situational Awareness fund was reported cutting public equity positions to meet margin with BofA, Goldman, and JPMorgan.
JPMorgan’s Nikolaos Panigirtzoglou wrote Wednesday that tech/semi/memory deleveraging moved faster than expected, leaving limited room for more. Read that as evidence the unwind pressure ran hot—not as a guarantee that risk is gone.
Liquidation cascades — why ‘flush then bounce’ looks scripted
A liquidation cascade is forced selling that pushes price further, which triggers more forced selling. Leveraged ETFs cut exposure on down days; margin accounts breach ratios; clustered stop orders add fuel.
Korea showed a local version: single-stock 2x ETFs on Samsung and SK Hynix, with mechanical futures rebalancing near the close amplifying cash-index swings. That reads less like a hunt and more like product design amplifying volatility.
So a crash-then-spike can look like stop hunting. Often the sequence is simpler: (1) leverage shrinks for a while, (2) a real catalyst arrives, (3) short covering and up-day ETF rebalancing buy into strength. July 30 fits that mix.
-
1
Price falls
-
2
Margin calls, stops, ETF selling
-
3
Further decline
-
4
Leverage cut / news digested
-
5
Catalyst + short cover / up-day rebalance
-
6
Sharp rebound
Thursday’s rebound — Azure flipped the switch
The surface switch was fundamental. Microsoft printed $90.0B in quarterly sales and Azure growth of +43% in constant currency (vs ~40% expected). Fiscal-year Azure above $100B argued that AI spend was turning into revenue.
Meta fell on free cash flow down about 91% year over year and soft guidance. The market’s question was not ‘do you spend on AI?’ but does the spend show up in sales and profits? Microsoft passed; Meta did not. Chips tagged along with the pass.
Layer on the prior deleveraging: after leverage has already been cut, the same good news meets less forced selling and more mechanical buying. That is closer to an unwind clearing, then a catalyst landing than to a staged hunt of 3x retail.
Was the tech broken — demand vs equity leverage
A 20–25% price drop does not mean HBM suddenly flooded or CoWoS packaging eased. Most commentary still cites tight HBM into 2027 and strong sector earnings-growth estimates. This correction was more about AI CapEx ROI and valuation doubt than ‘chips are not selling.’
Separate two questions: supply-chain demand (industry) versus who was leveraged how many times (finance). Healthy industry plus excessive leverage still produces violent equity paths. After leverage is cut, the same earnings print can bounce faster.
Even into the slide, roughly $24.7B flowed into major semi ETFs (SOXX, SMH, DRAM, SOXL), including about $5.1B into SOXL. Forced selling and dip-buying coexisted. Chasing with daily 3x means accepting reset costs on purpose.
Stop-hunt folklore vs structure
‘Stop hunting’ usually means a big player pushes into stop clusters, liquidates weak hands, then reverses. Thin books can overshoot. A multi-week sector −20% and SOXL −60%, though, lines up better with repricing + institutional delever + ETF mechanics in the public record.
- Real: margin calls, forced sales, daily ETF sell/buy, stop and credit cascades
- Easy to overstate: a single plot aimed only at retail 3x holders
- Practical takeaway: hold a one-day 3x product for weeks and the path becomes your P&L
For context, see our earlier semiconductor selloff and bottleneck outlook, the Korea–global ETF tax and fee guide for product structure, and US market correction and DXY history for the broader tape.
Takeaways
The 20–30% semiconductor drawdown and the July 30 spike are not one-line ‘they hunted 3x.’ What showed up in reporting is hedge-fund/prime deleveraging, leveraged-ETF daily resets, and Microsoft’s Azure switch. That mix deepened the slide and steepened the bounce.
After a −63% SOXL drawdown, simple math already needs about +170% to break even—and a choppy recovery can demand more. Bullish on chips is not the same as holding a 3x daily fund.
One line: Leverage can be right on direction and still wrong on path. A green Thursday does not refund weeks of structural decay. This is market-structure education, not investment advice. Figures and headlines will keep updating.
Leverage can be right on direction and still wrong on the path — daily resets do not forgive chop.
Sources
- CNBC — Jul 30 market / JPM delever
- Yahoo Finance — leverage cost of chip crash
- TechTimes — SOXL −63% vs SOXX −25%
- Motley Fool — MSFT Azure / chip rebound
- Chosun Biz — Korea leveraged ETF whiplash
- Khan Capital — SOX bear market
- Internal: 2026-07-31-semi-leverage-liquidation-rebound-session-01.md
For information only — this is not a recommendation to buy or sell any asset.
Comments 0