중국 신약 기술수출 — 선급금 6억달러, 한국 바이오의 경쟁은 더 세질까China drug licensing — what $600m upfront means for Korean biotech
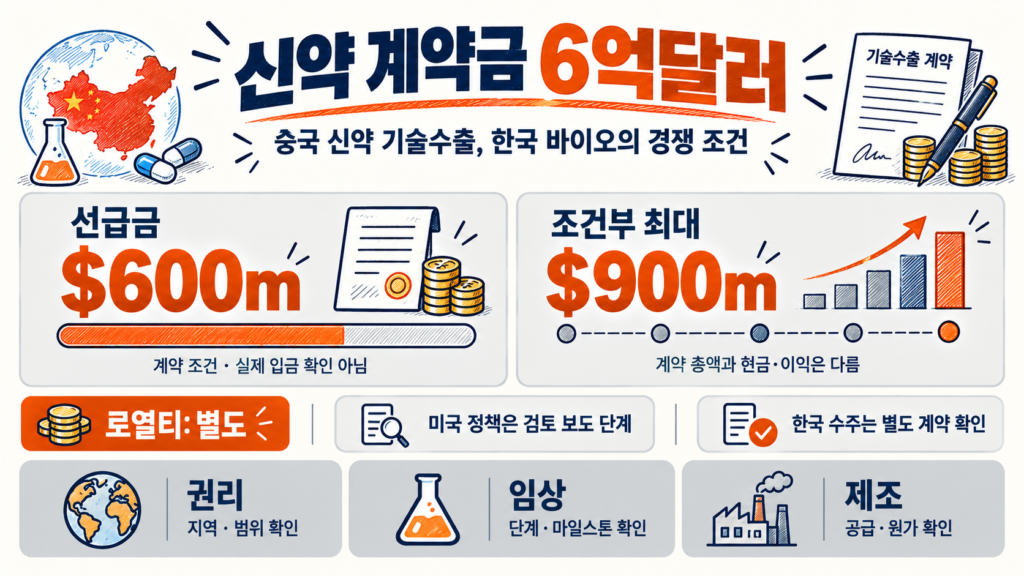
9월 1일, 아스트라제네카가 중국 디잘의 폐암약을 선급금 6억달러에 도입하는 계약을 완료했다고 발표했습니다. 중국 신약 기술수출이 한국 바이오에도 중요한 이유는 구매자의 선택지가 늘어나기 때문입니다. 비슷한 약을 개발하는 한국 기업이라면 계약 조건과 다음 임상시험에 쓸 자금까지 영향을 받을 수 있습니다. 아스트라제네카 발표
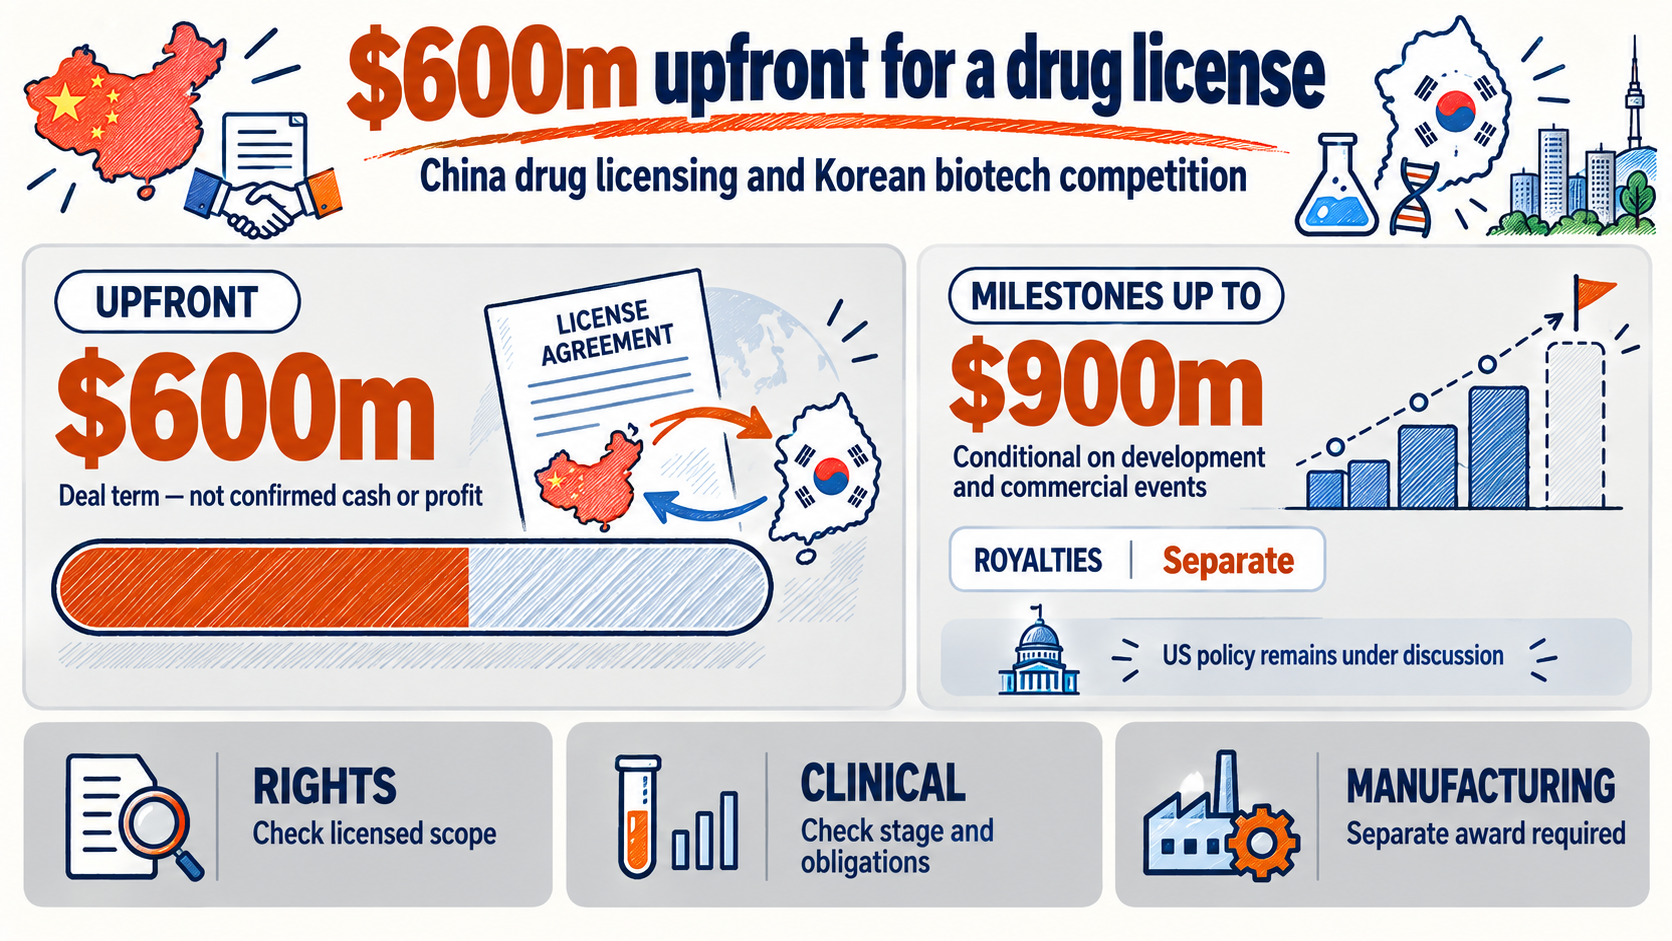
On September 1, AstraZeneca announced that it had completed a deal for Chinese developer Dizal’s lung-cancer drug, with $600 million payable upfront. China drug licensing matters for Korean biotech because it gives buyers more options. For a Korean company developing a similar medicine, that could affect both its negotiating terms and the money available for its next trial. AstraZeneca announcement
먼저 뉴스의 상태부터 구분해야 합니다. 9월 18일 Reuters는 미국이 중국 신약의 상당수 기술도입 거래를 계속 허용하는 방향의 규칙을 검토 중이라고 보도했습니다. 취재원을 통한 보도이며 확정된 규정은 아닙니다. 이 글은 2026년 9월 25일 확인한 자료를 기준으로, 정책 논의와 실제 계약을 나눠 읽습니다. Reuters 보도
중국 신약 기술수출, 왜 미국 제약사에도 필요한가
기술수출은 약 상자를 해외로 보내는 것과 다릅니다. 개발사가 가진 후보물질을 다른 회사가 특정 지역에서 개발하고 판매할 권리를 사는 거래입니다. 초기 연구를 한 회사와 대규모 임상시험·허가·판매를 맡는 회사가 달라도 됩니다.
사오는 회사 입장에서는 개발 시간을 줄일 기회입니다. 처음부터 후보물질을 찾는 대신 이미 쌓인 실험·임상자료를 평가할 수 있습니다. 파는 회사는 판매조직을 전 세계에 직접 만들지 않고도 연구 성과를 돈으로 바꿀 수 있습니다. 다만 그 대가로 미래 수익의 일부와 사업 통제권을 넘깁니다.
따라서 거래를 막으면 돈이 중국으로 가지 않는 효과만 생기는 게 아닙니다. 미국 기업의 신약 확보 선택지도 줄어듭니다. 반대로 거래를 열어두면 중국 개발사에는 후속 연구 자금이 돌아갑니다. 아래는 이 계약 구조에서 도출한 경제적 해석입니다. 실제 비용 절감 폭이나 성공 확률을 측정한 결과는 아닙니다.
-
1
초기 개발
개발사가 후보물질·자료 확보
-
2
권리 거래
구매자가 대가 지급·개발 역할 분담
-
3
후속 시험·판매
비용과 실패 위험은 계속 존재
-
4
연구 재투자
수취 자금이 다음 개발의 재원이 될 수 있음
6억달러와 9억달러는 같은 돈이 아닙니다
구체적인 사례가 디잘(Dizal)의 제그프로비(Zegfrovy)입니다. 아스트라제네카는 9월 1일 이 폐암약의 전 세계 개발·상업화 권리 계약을 완료했다고 발표했습니다. 계약상 선급금은 6억달러이고, 개발·허가·매출 관련 조건을 달성하면 지급하는 추가 대금은 최대 9억달러입니다. 매출에 연동하는 로열티는 별도입니다. 아스트라제네카 계약 공시
제그프로비 계약의 지급 구조 — 억달러. AstraZeneca 2026-09-01. 선급금 6, 조건부 대금 최대 9. 로열티 별도. 실제 입금액·이익 비교가 아닙니다.
두 금액을 더하면 15억달러입니다. 솔직히 이 숫자만 보면 연구비 걱정은 끝났다고 생각하기 쉽습니다. 실제로 쓸 수 있는 돈을 따지려면 지급 조건부터 봐야 합니다. 선급금은 계약 초기에 지급하기로 한 대가이고, 조건부 대금은 정해진 성과가 나와야 받을 수 있습니다. 발표문만으로 실제 입금일이나 해당 분기에 인식할 매출까지 확인할 수는 없습니다.
기술을 판 회사는 선급금으로 다음 시험을 진행할 여유가 생길 수 있습니다. 다만 현금이 들어오는 시점과 회계상 매출·이익을 기록하는 시점은 계약 의무에 따라 다를 수 있습니다. 조건부 대금을 모두 받을 것처럼 인건비와 연구비를 늘리면, 시험 일정이 밀릴 때 다시 자금조달을 해야 할 수도 있습니다.
사오는 회사도 계약 규모가 클수록 당장 이익이 커지는 것은 아닙니다. 계약 대금 외에 후속 임상, 생산 준비, 영업 비용이 더 들 수 있습니다. 앞으로 벌 돈의 가치가 이런 비용과 실패 위험을 감당할 만큼 큰지가 핵심입니다. 같은 신약이라도 도입 가격이 비싸지면 투자 매력은 낮아질 수 있습니다.
규제 검토와 거래 허용을 같은 말로 읽으면 안 됩니다
미 재무부 FAQ는 COINS Act에 따른 시행규정이 발행되기 전까지 기존 해외투자 규정과 의무가 유지된다고 설명합니다. 이 설명은 Reuters 보도의 의약품 허용 방안이 확정됐다는 증거가 아닙니다. 최종 규정에서 어떤 활동과 거래가 대상이 되는지 확인해야 합니다. 미 재무부 FAQ
라이선스와 지분투자도 구분해야 합니다. 라이선스는 약의 개발·판매 권리를 사는 것이고, 지분투자는 회사의 주주가 되는 것입니다. 실제로 화이자의 2025년 3SBio 거래 발표에는 두 방식이 함께 등장합니다. 같은 계약 묶음에 들어 있어도 권리의 성격이 다르므로, 한쪽의 취급만 보고 다른 쪽까지 자동으로 판단할 수 없습니다. 화이자 거래 완료 발표
아스트라제네카는 영국 기반 기업입니다. 앞서 본 계약은 중국 신약이 국제 거래의 대상이라는 사례이지, 미국의 향후 규정이 어떻게 적용될지를 입증하는 사례는 아닙니다. 실제 규제 적용은 거래 당사자와 구조 등 구체적인 요건에 달려 있습니다.
한국 바이오에는 기회와 가격 경쟁이 함께 옵니다
그럼 한국 기업에는 어떤 얘기일까요? 근데 여기서 한 가지, 한국산이라는 이유만으로 더 좋은 값을 받기는 어려울 수 있습니다. 중국 후보물질을 계속 도입할 수 있다면 글로벌 제약사는 더 많은 대안을 비교할 수 있기 때문입니다. 같은 질환을 겨냥한 비슷한 약이 여러 개라면 선급금 협상도 까다로워질 수 있습니다. 이런 조건에서는 약효, 부작용, 투약 편의성, 임상자료의 신뢰도가 협상력을 좌우할 것으로 봅니다.
반대로 비교 대상이 적은 기술이나 기존 치료의 불편을 분명히 줄이는 약은 선택받을 여지가 있습니다. 규제가 중국 거래를 제약하는 방향으로 정해지더라도 한국 기업 전체의 반사이익으로 계산하면 곤란합니다. 구매자는 다른 나라의 약을 찾거나 자체 개발을 늘리거나, 그 분야 투자를 미룰 수도 있기 때문입니다.
신약 개발사와 위탁개발·생산업체도 다르게 봐야 합니다. 위탁개발·생산업체는 다른 회사의 약을 공정에 맞춰 만들고 생산을 맡는 기업입니다. 기술수출이 늘어도 기존 제조시설을 그대로 사용하면 한국 공장에는 주문이 오지 않을 수 있습니다. 반대로 별도 생산처를 정하고 공정 이전을 진행한다면 그때 수주 가능성을 살필 근거가 생깁니다.
신약 개발사
개발·판매 권리 제공
돈을 받는 이유
경쟁 변수 · 임상자료·차별성·권리 범위
확인할 것 · 선급금·조건·잔여 연구비
위탁개발·생산업체
공정 개발·의약품 생산
돈을 받는 이유
경쟁 변수 · 품질·생산 역량·일정
확인할 것 · 별도 제조계약·공정 이전
연구 단계의 진전이 사업화로 이어지기까지 어떤 간격이 있는지는 ALK 분자접착제 개발 사례에서도 살펴볼 수 있습니다. 가상 세포 AI와 신약 실험비는 초기 연구의 비용 문제를 다룹니다. 이번 글의 거래·규제 사실을 뒷받침하는 출처가 아니라, 개발 과정의 서로 다른 단계를 이해하는 참고 글입니다.
개발비가 줄면 약값도 바로 내려갈까
환자 입장에서는 결국 병원에서 내는 돈이 궁금합니다. 연구개발에서 아낀 비용이 진료비에 도달하기까지는 몇 가지 문턱이 있습니다. 최종 가격에는 경쟁약의 유무, 특허, 보험 적용과 협상 조건 등이 영향을 줍니다. 도입 기업이 비용을 아껴도 그 혜택을 환자에게 얼마나 전달할지는 별도 문제입니다. 더 많은 약이 개발·출시돼 치료 선택지가 늘어나는 효과와, 환자의 본인부담금이 줄어드는 효과를 구분해야 합니다.
허가도 확인할 필요가 있습니다. FDA가 제그프로비에 내린 2025년 승인은 특정 유전자 변이가 있고 기존 백금항암 치료 후 병이 진행한 비소세포폐암 성인환자를 대상으로 한 신속승인입니다. 모든 폐암 환자에게 쓸 수 있다는 뜻은 아닙니다. 신속승인은 후속 시험으로 임상적 이익을 확인하는 절차와 연결됩니다. FDA 승인 발표 · 신속승인 제도
거시경제 효과는 더 신중하게 봐야 합니다. 선급금이 들어온 기업은 연구 인력과 시험 비용을 늘릴 수 있고, 생산 계약까지 이어지면 설비투자도 움직일 수 있습니다. 하지만 권리 거래가 곧바로 국내 공장 생산이나 가계 소비 증가를 뜻하지는 않습니다. 현재 확인한 계약 자료만으로 한국 성장률이나 고용 효과를 숫자로 추정하기는 어렵습니다.
바이오 주가를 볼 때는 계약 총액 다음을 읽습니다
바이오기업 가치는 아직 들어오지 않은 돈에 크게 좌우될 수 있습니다. 투자자는 미래 수입에서 남은 연구비를 빼고, 실패 가능성과 돈을 기다리는 시간을 반영해 현재 가치를 따집니다. 계약 성사 가능성이 높아지면 주가에 우호적일 수 있지만, 경쟁 후보가 늘어나 예상 선급금이 내려가면 반대 효과도 생깁니다. 이번 보도가 특정 주가를 움직였다는 실증 주장은 아닙니다.
앞으로는 미국의 최종 규정 문구, 기업 공시의 실제 수취액과 잔여 의무, 후속 임상·허가 진행을 함께 확인할 필요가 있습니다. 생산 수혜를 논하려면 제조처와 계약도 확인해야 합니다. 아스트라제네카가 밝힌 미국 4분기 출시는 회사 계획이므로, 실제 출시와 매출 발생을 구분해서 볼 사안입니다. 회사 발표
중국 신약 기술수출의 통로가 열릴수록 한국 기업에는 실력으로 비교받는 시장이 커질 수 있습니다. 그래서 계약을 읽을 때 가장 실용적인 질문은 이것입니다. 지금 받을 돈은 얼마이고, 다음 돈을 받으려면 무엇을 더 증명해야 할까요? 이 글은 산업 구조를 설명한 분석이며 개별 종목의 투자 권유는 아닙니다.
지금 받을 돈은 얼마이고, 다음 돈을 받으려면 무엇을 더 증명해야 할까요?
출처
On September 18, Reuters reported that US officials were considering rules that would preserve many licensing deals for Chinese medicines. This was a sourced report about deliberations, not a final rule. This article separates that policy uncertainty from completed transactions, using information checked on September 25, 2026. Reuters report
Why global drugmakers want Chinese drug licenses
Licensing is different from shipping boxes of medicine abroad. A developer grants another company rights to develop and sell a drug in specified territories. Early discovery, large trials, regulatory work and commercial distribution can therefore sit in different businesses.
The buyer gets a chance to shorten development by evaluating work already done. The seller can fund its science without building a worldwide sales organization, but gives up some control and future economics in return.
Restricting these transactions could reduce both financing for Chinese developers and the options available to US buyers. Keeping them open could finance another generation of Chinese research. This is an economic interpretation of the structure, not a measured estimate of cost savings or clinical success.
-
1
Early development
Developer builds an asset and evidence
-
2
License agreement
Buyer pays and takes agreed responsibilities
-
3
Trials and sales
Further cost and failure risk remain
-
4
Research reinvestment
Receipts can finance another program
$600 million upfront is different from $900 million contingent
On September 1, AstraZeneca announced completion of its agreement for worldwide development and commercial rights to Dizal’s Zegfrovy. It disclosed $600 million upfront and up to $900 million tied to development, regulatory and sales milestones, plus separate royalties. AstraZeneca announcement
Zegfrovy payments — USD 100 million. AstraZeneca, Sep 1, 2026. Upfront 6; milestones up to 9. Royalties separate. Not cash received or profit.
Add them up and you get $1.5 billion. At first glance, that sounds like the research budget is sorted. The payment terms tell you how much the developer can actually count on: upfront consideration is payable at the start, while milestones depend on specified outcomes. The announcement alone does not establish the exact receipt date or quarterly revenue recognition.
For the seller, upfront funding can support the next trial. Cash collection and reported revenue or profit can occur at different times depending on contractual obligations. Expanding research spending on the assumption that every milestone will arrive can create another funding need if trials slip.
For the buyer, a larger agreement does not automatically mean higher near-term profit. Further trials, manufacturing preparation and commercialization can require additional spending. The relevant question is whether future earnings justify the acquisition price, remaining costs and risk of failure.
A policy discussion does not settle every transaction
Treasury’s FAQ says the existing outbound investment rules remain in effect until regulations implementing the COINS Act are issued. That does not confirm the pharmaceutical approach described by Reuters. The final text must establish which activities and transactions are covered. US Treasury FAQ
A license buys drug rights; an equity investment buys ownership in a company. Pfizer’s 2025 announcement concerning 3SBio included both. These are distinct rights even when negotiated together, so treatment of one component does not automatically establish treatment of the other. Pfizer announcement
AstraZeneca is based in the UK. Its agreement illustrates the international market for Chinese medicines; it is not proof of how a future US rule would apply. Applicability depends on the parties, structure and specific requirements.
Korean biotech faces opportunities and tougher bargaining
So where does that leave Korean developers? Being Korean may not, by itself, command a better price. If buyers retain access to Chinese candidates, they have more alternatives to compare. Similar medicines targeting the same condition could face tougher upfront-payment negotiations. In that scenario, we would expect efficacy, safety, convenience and reliable clinical evidence to carry more weight.
Differentiated technology can still attract buyers. Even if restrictions increase, however, Korea does not automatically capture the displaced spending. Buyers could turn to other countries, invest internally or postpone the program altogether.
Drug developers and contract manufacturers face different economics. A contract manufacturer develops production processes or makes another company’s medicine. More licensing deals need not produce Korean orders if existing manufacturing arrangements remain in place. A separate supplier decision and technology transfer would provide stronger evidence of an opportunity.
Drug developer
Licensing development and sales rights
Revenue driver
Competition · Evidence, differentiation and rights
Evidence needed · Upfront, milestones and remaining R&D
Contract manufacturer
Process development and manufacturing
Revenue driver
Competition · Quality, capacity and timing
Evidence needed · Manufacturing award and tech transfer
For related reading on the distance between research and commercialization, see our ALK molecular-glue article. Our virtual-cell AI article covers early research costs. These are background reading, not evidence for the transactions or policy claims discussed here.
Will cheaper development lower the price patients pay?
Lower development costs need not immediately lower patient bills. Prices also depend on competing treatments, patents, insurance coverage and negotiations. More treatment options and lower out-of-pocket spending are separate outcomes; the latter requires savings to reach patients.
Zegfrovy’s 2025 FDA accelerated approval covered adults with a specified EGFR mutation whose advanced non-small cell lung cancer had progressed after platinum chemotherapy. It was not approval for all lung cancers. Accelerated approval also requires subsequent confirmation of clinical benefit. FDA approval notice; Accelerated Approval Program
The macroeconomic effects are more indirect. Licensing receipts can finance researchers and trials; a manufacturing award could support capital expenditure. A rights transaction alone does not establish higher Korean factory output or household consumption. These announcements do not support a numerical estimate of Korea’s GDP or employment impact.
For biotech valuations, read beyond the headline total
Biotech valuations can depend heavily on money not yet earned. Investors weigh future receipts against remaining research costs, failure risk and the wait for payment. Better deal prospects can help valuations, while tougher competition can lower expected terms. This is a valuation mechanism, not a claim that this report caused a particular share-price move.
Watch the final US rules, disclosed cash receipts and obligations, and subsequent trial and approval developments. Manufacturing claims need manufacturing evidence. AstraZeneca’s stated fourth-quarter US launch is a company plan; actual launch and revenue remain separate checkpoints. Company announcement
An open market for China drug licensing could enlarge the arena in which Korean developers must demonstrate differentiation. The practical questions are how much is payable now and what must be proven to earn the next payment. This is industry analysis, not a recommendation to invest in a security.
How much is payable now, and what must be proven to earn the next payment?
Sources
이 글은 정보 제공 목적이며, 특정 자산의 매수·매도를 권유하지 않습니다.
For information only — this is not a recommendation to buy or sell any asset.
댓글Comments 0