중국 주택과 소비 — 약 40%가 보여주는 집값 부양의 한계China housing and consumption — the limits behind the 40% figure
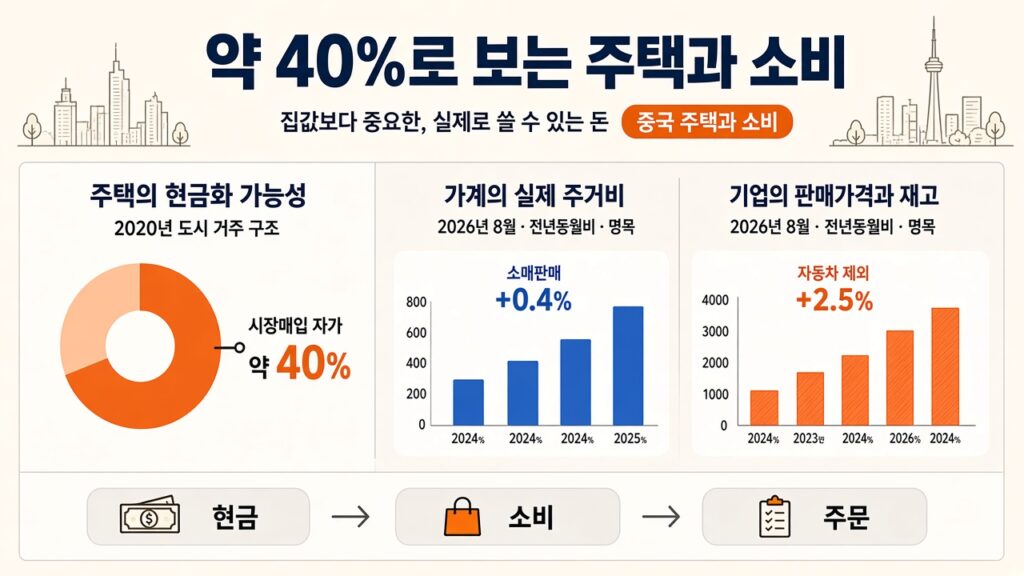
중국 주택과 소비를 볼 때, 집값만으로는 놓치는 가계가 많습니다. 9월 18일 나온 IMF 연구에서 시장에서 산 자가주택은 도시 거주 주택의 약 40%입니다. 집을 어떤 방식으로 보유하는지가 왜 소비 여력과 한국 기업의 판매 전략을 바꾸는지 짚어봅니다.
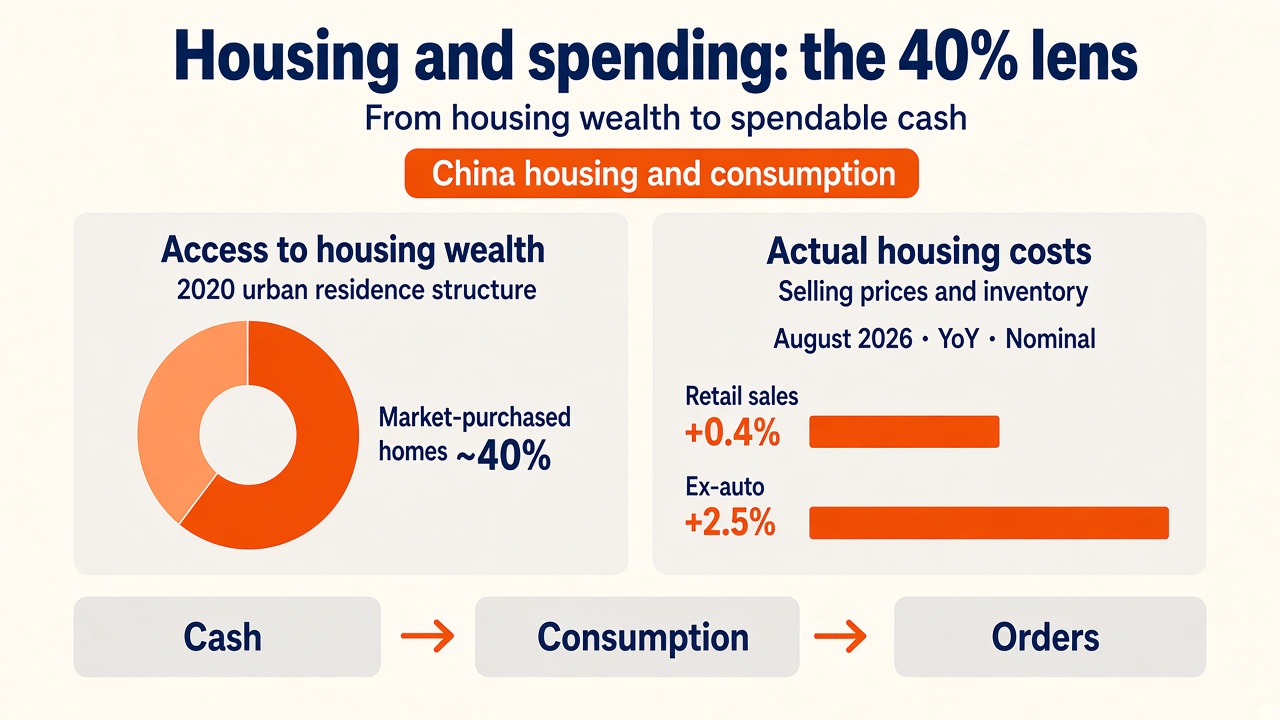
China housing and consumption cannot be understood through property prices alone. An IMF working paper released on September 18 puts market-purchased homes at about 40% of occupied urban dwellings. The distinction offers a useful starting point for thinking about household spending and Korean companies selling into China.
이 비율은 2020년 인구총조사에 근거한 구조 설명이며, 올해 새로 조사한 수치는 아닙니다. 연구는 시장매입 자가·임차·비시장 취득 자가를 구분합니다. 마지막 유형은 상속이나 과거 공공주택 할인 분양 등으로 취득한 집을 뜻합니다. 소득과 자산 등을 고려해도 소비 양상은 달랐지만, 이를 인과관계로 입증한 것은 아닙니다. IMF 연구 원문
여기서부터의 기업·정책 분석은 그 구분을 활용한 해석입니다. 집값을 올리는 조치와 가계가 이번 달 쓸 돈을 늘리는 조치는 같은 효과를 내지 않을 수 있습니다. 이 차이를 놓치면 부동산 부양 소식을 듣고 소비재 기업의 이익 전망부터 지나치게 높이기 쉽습니다.
중국 주택과 소비, 먼저 최신 판매 숫자부터
중국 국가통계국에 따르면 2026년 8월 소비재 소매판매는 전년 같은 달보다 0.4% 늘었습니다. 자동차를 제외하면 증가율은 2.5%입니다. 자동차를 포함하느냐에 따라 체감 경기가 달라지는 셈입니다. 국가통계국 세부 발표
8월 소매판매, 자동차를 빼면 달라지는 숫자. 출처: 중국 국가통계국, 2026년 8월. 명목 금액 기준. 두 계열은 포함 관계이며 성장 기여도 비교가 아닙니다.
두 값은 모두 물가 변화를 제거하지 않은 명목 증가율입니다. 이 소매판매 지표에는 재화와 외식이 포함되지만 모든 서비스 소비가 들어가지는 않습니다. 전체 증가율 0.4%는 9월 15일 종합 발표와 대조했습니다. 같은 통계체계의 두 발표를 확인한 것이며, 별도의 조사로 재현했다는 뜻은 아닙니다.
이 숫자만으로 소비 부진의 원인을 주택에서 찾을 수는 없습니다. 자동차 구매 시점, 가격 할인, 전년의 비교 기준도 영향을 줄 수 있습니다. 다만 소비가 얼마나 늘었는지와 왜 늘지 못하는지를 나눠 볼 필요는 분명합니다. 최신 판매 통계는 현재를 보여주고, 주거 구조는 가계마다 반응이 달라질 수 있는 이유를 생각하게 합니다.
집 한 채와 통장 잔액은 다르게 움직입니다
가령 시세가 오른 집에 계속 살아야 하는 가계를 생각해 보겠습니다. 집을 팔면 현금이 생기지만 다른 거처를 마련해야 합니다. 더 작은 집으로 옮기거나 추가 대출을 받지 않는 한, 오른 집값 전부를 생활비로 쓸 수는 없습니다. 재산이 늘었다는 느낌과 실제로 지출할 수 있는 돈 사이에는 거리가 있습니다.
주택의 유동성도 중요합니다. 유동성은 자산을 큰 손실 없이 현금으로 바꾸기 쉬운 정도입니다. 거래가 잘 되는 집과 매각에 제약이 있는 집은 장부상 가격이 같아도 다르게 작동합니다. 급하게 현금이 필요한 가계라면 후자를 보유하고 있어도 여행이나 가전 교체를 미룰 수 있습니다.
반대로 세입자에게 집값 상승은 당장 쓸 돈을 늘려주지 않습니다. 내 집 마련을 준비 중이라면 필요한 저축 목표가 더 커질 수도 있습니다. 집값 상승이 소비를 늘린다는 설명에는 누가 집을 갖고 있는지, 대출이 얼마나 남았는지, 앞으로 집을 살 계획인지가 함께 들어가야 합니다.
이것은 가능한 경제적 경로를 풀어 쓴 설명입니다. 앞선 논문이 각 경로의 크기를 따로 입증했다는 뜻은 아닙니다. 같은 이유로 중국의 과거 표본에서 나온 관계를 한국 가계의 소비 증가율에 그대로 대입하지 않았습니다.
부동산 부양책의 효과는 돈이 어디에 닿느냐에 달렸습니다
정책을 읽을 때는 발표 금액보다 가계의 어떤 부담이 줄어드는지를 먼저 확인할 만합니다. 대출금리가 내려가더라도 기존 계약의 이자가 언제 바뀌는지에 따라 효과가 늦게 나타날 수 있습니다. 줄어든 이자를 추가 원금 상환에 쓰면 소비로 넘어가는 돈은 작아집니다.
주거비가 줄어드는 경우에도 고용이 불안하면 가계는 먼저 비상자금을 채울 수 있습니다. 반대로 소득이 안정되고 현금 여유가 생기면 미뤘던 수리나 교체 지출이 나올 가능성이 커집니다. 정책 발표에서 기업 매출까지는 이런 선택을 여러 번 거칩니다.
-
1
주거비 감소
이자·임차료 부담이 실제로 줄어듦
-
2
현금 배분
저축·빚 상환·소비 중 선택
-
3
소비자 구매
소득 안정 시 교체·수리 가능
-
4
기업 주문
유통 재고 소진 뒤 재주문
주택 거래 회복과 신규 건설 회복도 구분해야 합니다. 기존 주택이 주인을 바꾸면 중개·이사·인테리어 수요가 생길 수 있습니다. 그러나 그 거래가 새 아파트 착공이나 건설자재 주문으로 반드시 이어지지는 않습니다. 어떤 거래가 늘었는지 알아야 수혜 업종도 가려집니다.
한국 기업은 중국 매출을 고객과 제품으로 나눠 봐야 합니다
한국 기업에 대한 다음 설명은 조건부 시나리오입니다. 특정 회사가 이미 이런 실적 변화를 겪었다는 주장은 아닙니다. 중국에서 파는 제품이라도 새집 입주 때 사는 제품인지, 기존 제품이 고장 나서 바꾸는 것인지에 따라 주택 경기와의 연결이 다릅니다.
프리미엄 가전은 구매를 늦추거나 더 저렴한 모델로 바꾸기 쉽습니다. 이 경우 판매 대수가 유지돼도 평균 판매가격은 낮아질 수 있습니다. 평균 판매가격은 매출을 판매 수량으로 나눈 값입니다. 고가 제품 비중이 줄고 판촉비까지 늘면 매출보다 이익이 더 약해질 수 있습니다.
수리·교체 수요는 다른 질문을 던집니다. 집을 새로 사지 않아도 생활에 필요한 제품은 바꿔야 합니다. 다만 교체 수요가 있다는 사실이 한국 브랜드의 점유율 상승을 보장하지는 않습니다. 현지 경쟁사의 가격, 수리망, 유통 수수료를 함께 봐야 합니다.
프리미엄 신규 구매
구매 연기·저가 모델 전환
가계 선택
실적 변수 · 평균 판매가격·판촉비
필요한 수리·교체
주택 구매 없이도 지출 가능
가계 선택
실적 변수 · 경쟁 가격·수리망·유통비
여기서 재고가 실적의 다음 변수가 됩니다. 제조사가 유통업체에 납품하면 제조사의 매출이 늘어날 수 있습니다. 하지만 소비자 판매가 따라오지 않으면 유통업체 창고에 물건이 쌓입니다. 다음 주문은 줄고, 재고를 털기 위한 할인 지원 요청은 커질 수 있습니다.
따라서 기업 발표에서는 중국 매출 성장률과 함께 최종 소비자 판매, 유통 재고, 할인 부담을 확인할 필요가 있습니다. 최종 판매가 안정되기 전에 생산능력을 늘리면 공장 가동률이 낮아질 위험이 있습니다. 가동률이 떨어지면 공장 임차료·감가상각 같은 고정비를 더 적은 제품에 나눠 부담하게 됩니다.
소비재 주가의 반등과 이익 회복은 시차가 있습니다
자산시장은 실제 주문보다 정책 기대에 먼저 반응할 수 있습니다. 부동산 지원 발표 뒤 소비재 주가가 오른다면 시장이 회복 가능성을 더 높게 평가한 것으로 볼 수 있습니다. 그러나 주가 상승 자체가 소비 회복을 확인해주는 자료는 아닙니다. 이후 실적에서 판매가격과 이익률이 따라오는지를 봐야 합니다.
경기 흐름을 판단할 때도 부동산 거래, 가계 소득, 소매판매를 하나의 신호로 묶지 않는 편이 좋습니다. 거래가 살아나도 가계가 대출을 먼저 줄이면 소비 확산은 느릴 수 있습니다. 소비가 늘어도 수입 제품보다 현지 저가 제품에 집중된다면 한국 기업에 돌아오는 몫은 제한됩니다.
이와 연결해 중국 내수와 K자 경제는 산업별 온도 차이를, 미국 주택 착공과 건설사 할인은 거래량과 수익성이 달라지는 사례를 다룹니다. 이번 글의 초점은 산업 전체의 평균보다 가계가 실제로 쓸 수 있는 돈에 있습니다.
다음 통계와 실적에서 확인할 것은 단순합니다. 자동차를 뺀 소비가 얼마나 넓게 살아나는지, 주거 관련 지출이 신규 구매인지 교체인지, 기업의 재고와 할인 부담이 줄어드는지입니다. 세 가지가 함께 개선된다면 소비 회복이 기업 이익으로 이어진다는 해석에 힘이 실립니다. 하나만 좋아졌다면 아직 다른 설명이 가능한 상태입니다.
집값을 떠받치는 정책이 나왔다는 이유만으로 소비 회복을 확정하기는 어렵습니다. 집을 가진 사람이 누구인지, 그 집을 현금으로 바꿀 수 있는지, 월급에서 주거비를 빼고 얼마가 남는지가 기업의 다음 주문을 결정합니다. 자료 확인 기준일은 2026년 9월 26일이며, 이 글은 특정 자산의 매수·매도 권유가 아닙니다.
소비 회복은 집값뿐 아니라 가계가 실제로 쓸 수 있는 돈에서 확인해야 합니다.
출처
The share describes the 2020 census, not a fresh 2026 survey. The paper distinguishes market buyers, renters and owners who acquired homes outside the market, such as through inheritance or discounted public-housing sales. Consumption patterns differ after controlling for income and wealth, but the evidence does not establish causality. IMF paper
The business and policy discussion below is our interpretation. Supporting asset prices and increasing the cash a household can spend this month are different interventions. Treating them as interchangeable can produce overly optimistic earnings assumptions for consumer companies.
China housing and consumption: start with the latest sales
China’s consumer-goods retail sales grew 0.4% from a year earlier in August 2026. Excluding automobiles, growth was 2.5%. The automobile category therefore matters when interpreting the headline. NBS detailed release
August retail sales: the automobile difference. Source: NBS, August 2026. Nominal growth. Overlapping series, not growth contributions.
Both are nominal growth rates, without a price adjustment. The measure includes goods and catering, rather than all services. We checked the 0.4% headline against the September 15 overview; this is consistency checking within the official statistical system, not an independent replication.
These figures do not prove that housing caused weak spending. Purchase timing, discounts and the comparison base can all matter. Current sales data tell us what is happening; household balance sheets help us ask why different customers might respond differently to the same economic news.
A home is not a bank balance
Consider a household whose home has risen in value but which still needs to live there. Selling releases cash, yet replacement accommodation costs money. Unless the family downsizes or borrows, the entire capital gain is not available for everyday purchases. Feeling wealthier and having money available are separate conditions.
Liquidity means being able to turn an asset into cash without a large loss. Two homes with similar estimated values can provide different financial flexibility if one is hard to sell. A cash-constrained owner may postpone a holiday or appliance replacement despite appearing wealthy on paper.
For a renter, rising property prices do not directly create spending money. Someone saving to buy may instead face a higher savings target. Any claim that higher home prices lift consumption needs to specify ownership, debt obligations and plans to purchase a home.
These are possible economic mechanisms, not separately proven effects from the paper. Nor do we transfer estimates from historical Chinese households into forecasts for Korean household spending.
The route from housing support to spending
When assessing policy, ask which household burden actually falls. A lower lending rate may reach existing borrowers only when their contracts reset. If borrowers use the savings to repay principal, the immediate increase in consumption can be modest.
Even with lower housing costs, a household worried about employment may rebuild emergency savings first. Stable income and more cash available could make postponed repairs or replacements more likely. Corporate revenue comes after these household decisions, not immediately after a policy announcement.
-
1
Lower housing costs
Actual relief in interest or rent
-
2
Cash allocation
Save, repay debt or spend
-
3
Consumer purchases
Replacement or repairs if income feels secure
-
4
Business orders
Reorders after inventory is absorbed
A revival in home transactions also differs from a revival in construction. Existing-home turnover may generate brokerage, moving and refurbishment demand without requiring new buildings. The type of transaction determines which businesses might benefit.
Korean companies need a customer-level view
The following are conditional scenarios for Korean businesses, not claims about reported results at particular companies. A product bought when moving into a new home has a different connection to property conditions from one bought to replace a broken item.
Premium appliances can be postponed or replaced by cheaper models. Unit sales may hold up while average selling prices decline. That average is revenue divided by units sold. A less profitable product mix, combined with higher promotion costs, can put greater pressure on earnings than on revenue.
Repair and replacement demand poses a different question. Some products need replacing without a home purchase. That does not guarantee market-share gains for Korean brands: local competitors’ prices, service networks and distribution charges still matter.
Premium purchases
Delay or trade down
Household choice
Earnings variable · Average price and promotions
Necessary replacement
Can occur without a home purchase
Household choice
Earnings variable · Competition, service and distribution costs
Inventory is the next earnings variable. Shipments to distributors can raise a manufacturer’s revenue even if sales to consumers lag. Unsold goods then accumulate in warehouses. Subsequent orders may weaken while requests for promotional support increase.
Company disclosures are more informative when China revenue growth is accompanied by consumer sell-through, distributor inventory and discounting trends. Expanding capacity ahead of durable final demand risks lower utilization. Factory rent and depreciation then have to be spread over fewer products.
Share prices can move before profits recover
Equity markets can react to policy expectations before orders improve. A rally in consumer stocks may reflect a higher probability assigned to recovery. The rally itself does not verify that recovery. Subsequent selling prices and margins provide a different kind of evidence.
Housing transactions, household income and retail sales should remain separate signals. A transaction recovery can coexist with slow spending if households prioritize debt reduction. Stronger consumption may still offer limited gains to Korean suppliers if demand concentrates on cheaper local products.
For related context, see China’s uneven domestic economy and US housing starts and builder discounts. This article focuses on households’ spendable cash, a different lens from aggregate sector performance.
The next releases should help answer three practical questions: Is spending strengthening beyond automobiles? Is housing-related demand driven by new purchases or replacement? Are inventories and discount burdens easing? Improvement across all three would strengthen the case for an earnings recovery. One positive indicator leaves room for other explanations.
Housing support alone is insufficient evidence of a consumer recovery. Ownership, the ability to access housing wealth, and income left after housing costs all matter for the next order. Information was checked as of September 26, 2026. This article does not recommend buying or selling any asset.
Look for a consumer recovery in spendable cash as well as property prices.
Sources
이 글은 정보 제공 목적이며, 특정 자산의 매수·매도를 권유하지 않습니다.
For information only — this is not a recommendation to buy or sell any asset.
댓글Comments 0